TGViewer
Channel Public Channel
Metals Wire

Metals Wire

@metalswire

Global Metals&Mining Research from Glush&Team. No investment advice, just numbers & charts!
Subscribers
696
Photos
2.7K
Videos
1
Links
1.9K

Showing posts older than #2570 · Back to latest

Older Posts 18 shown
Post #2569 135
Morning Bites

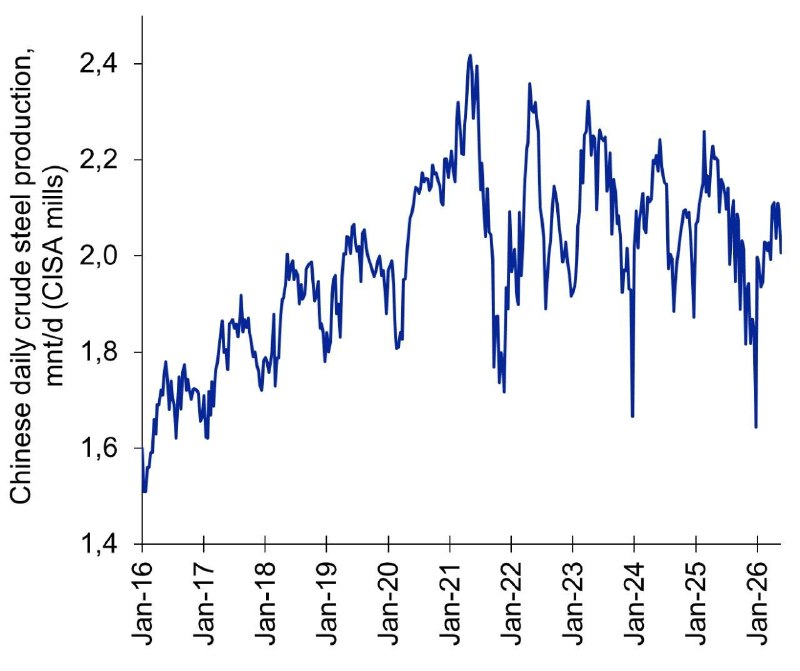
🔗CISA mills daily crude steel production in late-May was 2.00mnt, down 4.3% from the previous ten days, and 4.1% lower YoY. Per CISA data, local production has declined 5.9% YTD (through 31 May). Meanwhile, local steel inventories dropped 15.7% over the period, but were 3.5% higher YoY

Given the ongoing weakness in the global steel market, we believe that Beijing will continue to tighten supply on a gradual basis. Even though the current five-year plan lacks explicit targets for capacity cuts, China might also introduce additional strict supply-control measures, similar to the 2016-17 reform (when >100mnt steelmaking capacities were removed)

For instance, China has already released a tougher steel capacity swap plan to curb oversupply. Per a Ministry of Industry and Information Technology statement, at least 1.5t of old steel capacity now needs to be decommissioned to build ⁠every 1.0t of new capacity nationwide

#steel
Post #2568 130
Morning Bites (part 2)

🚘US light vehicle sales were flat YoY in May, vs. the 7% YoY drop in April. Total car sales in the US were 9% below their pre-Covid (May 2019) level

Meanwhile, the share of catalyst-containing cars in local sales is set to gradually increase, we believe, as US budget legislation eliminated USD 7,500 and USD 4,000 tax credits for buying new and used EVs, respectively, from the end of September 2025. In our view, this factor will further weigh on BEV sales in the US (~8% of global BEV registrations in 2025), as was the case in Germany in early-2024, which is supportive for PGM market fundamentals

On our numbers, North America accounted for 24% and 15% of world autocatalyst Pd and Pt consumption, respectively, in 2024

#cars #PGMs
Post #2566 119
Morning Bites (part 1)

🔗China’s net finished steel exports declined 2% YoY in May, vs. the 9% YoY drop in April. On a 5mo26 basis, net exports slid 8% YoY. Although China aims to further reduce “excessive” steel output in 2026 (which was also -4% YoY in 2025) — and strictly prohibits new capacity additions — exports (which increased 25% YoY in 2024 and 8% YoY in 2025) remain close to historical highs. Even though the current five-year plan lacks explicit targets for capacity cuts, further gradual supply-side measures could help rebalance the market and support steel prices, we believe

🪨China’s coal imports fell 8% YoY in May, following the 13% YoY decline in April. The China Coal Transportation and Distribution Association (CCTD) expects local coal imports to decrease 5% YoY 465mnt in 2026, given the upcoming supply restrictions in Indonesia. Per Reuters, Chinese traders are waiting more details on the new Indonesian export ⁠regulation

#coal #steel
Post #2565 126
🗞Today, China published its preliminary import/export statistics for May (see table above)

#statistics #China
Post #2564 142
Morning Bites

🚘New car registrations in France, the UK, Spain, Italy and Germany rose 3% YoY in May, vs. the 8% YoY gain in April. Total sales, however, remained below their pre-COVID level (24% lower than May 2019)

Specifically, in France, car sales were 34% beneath their 2019 level, while registrations in Italy and Germany decreased 24% and 28%, respectively. The UK figure was 13% less than 2019; Spain's 11% lower

Given these five countries represented more than 70% of new vehicle registrations in Europe in 2025, the region’s car sales likely increased YoY last month, while remaining well below their pre-pandemic levels

#cars #PGMs
Post #2563 147
Morning Bites (part 2)

⛏️ Codelco has signalled a strategy shift toward profitability over production volume, Bloomberg reports, citing the miner’s new chairman Bernardo Fontaine. The board has also called for a review of the calculation of 2024-25 production figures after the discovery of overcounting. Meanwhile, Codelco’s output (~6% of global mined Cu supply) dropped 8% YoY in 1Q26, amid declining ore grades and the fatal accident at the El Teniente mine in 2025

We maintain our bullish view on copper, amid both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2562 142
Morning Bites (part 1)

📉 Gold-backed ETFs sold 16t of gold net in May, reversing from the 45t net purchase in April, per World Gold Council data. The outflows mainly came from North America and Asia (-9t each) last month. Meanwhile, since May 2024, global funds have added 1,036t net (~11% of world physical gold demand, in annualised terms)

Although, at spot, gold continues to trade above what we see as its fundamentally reasonable level, we believe that the precious metal’s price will remain elevated in 2026. Moreover, intense inflationary pressure, if high oil prices persist, might eventually trigger a bull-run in gold prices, as happened in 1978-1980

#ETF #gold
Post #2561 120
Morning Bites

🏦 Global central banks purchased net 19t of gold in April, reversing from the revised 53t net sale in March, World Gold Council data show. Specifically, the major buyers in April were Poland (14t) and China (8t), which outweighed Russia’s sales (-6t)

Although, at spot, gold continues to trade above what we see as its fundamentally reasonable level, we believe that the precious metal’s price will remain elevated in 2026, as global ETFs and central banks returned to gold buying in April, as we expected. Moreover, intense inflationary pressure, if high oil prices persist, might eventually trigger another bull-run in gold prices, as happened in 1978-1980

#gold
Post #2560 132
Morning Bites

💍Hong Kong jewellery and watch sales grew 19% YoY in April, vs. the 26% YoY gain seen in March, per government data. Rapaport reports that the local authorities anticipate steady sales growth, with a boost from higher inbound tourism (the number of Mainland visitors was up 18% YoY in 4mo26) and stronger consumer confidence

However, we maintain our cautious view on the medium-term prospects for a recovery in the global diamond market, given the risks to supply discipline posed by Anglo American's planned sale of De Beers (which is currently disrupting the price-over-volume strategy), as well as geopolitical/trading concerns

#diamonds
Post #2559 122
Morning Bites

🌏 Global manufacturing PMIs were generally strong in May. The Eurozone Markit Manufacturing PMI printed 51.6 last month (vs. 52.2 in April), while the US ISM Manufacturing PMI jumped to 54.0 (the highest point since May-22)

🇨🇳 The official NBS Manufacturing PMI in China inched down to 50.0 (from 50.3 a month ago). Meanwhile, the Caixin China Manufacturing PMI slid to 51.8 (from 52.2 earlier)

🇮🇳 India’s manufacturing PMI of 55.0 remains one of the strongest indicators among the world's key economies

❗️Overall, manufacturing PMI readings in every major region were in neutral or positive (above 50.0) zone in May: this could be a positive sign for local industrial metals demand, if the trend persists, we think. At the same time, India remains the standout with continuously robust PMI figures

#PMIs
Post #2558 135
Morning Bites

🇨🇱Chile’s copper output dropped 14% YoY in April to the lowest point in the last 10 years, after the 9% YoY decrease in March, per INE data. The production decline was mainly attributable to the high base effect, as well as lower ore grades at major mines

We remind readers that Chile (~24% of global mined Cu supply) has recently revised down its medium-term Cu production forecast amid falling ore grades and adjusted mining plans. Specifically, its outlook for 2026 is 6% below the previous estimate (implying only moderate YoY growth of 2-3%)

We maintain our bullish view on copper, amid both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2557 142
Morning Bites

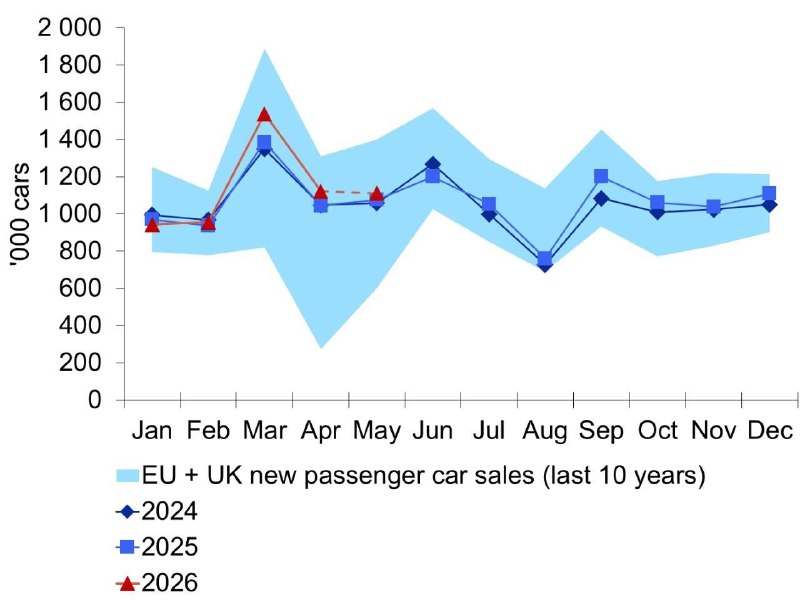
EU + UK passenger car registrations increased 7% YoY in April, vs. the 11% YoY gain in March, per ACEA data. The numbers were broadly in-line with preliminary estimates. The overall figure, however, was still 14% lower than the pre-Covid level (April 2019). Specifically, local catalyst-containing car sales gained 1% YoY, while BEV registrations surged 41% YoY last month

In our view, PGM supply issues (e.g., recent SBSW guidance until 2040), cancellation of EV-support programmes in the US (from late-September 2025), as well as potentially higher PGM autocatalyst loadings in China in the coming years (due to planned China 7 emissions standard), might bolster Pd/Pt market fundamentals in the medium term. Moreover, inflationary pressure, if high oil prices persist, could eventually trigger a bull-run in precious metals prices, we believe

In 2025, the EU+UK accounted for some 23% and 25% of world autocatalyst Pd and Pt demand, respectively

#cars
  • ❤ 1
Post #2556 124
Morning Bites

🔗CISA mills daily crude steel production in mid-May was 2.10mnt, down 0.7% from the previous ten days, and 4.7% lower YoY. Per CISA data, local production has declined 6.0% YTD (through 20 May). Meanwhile, local steel inventories rose 11.2% over the period, and were 14.8% higher YoY

Given the ongoing weakness in the global steel market, we believe that Beijing will continue to tighten supply on a gradual basis, even though the current five-year plan lacks explicit targets for capacity cuts. After a surge of exports in 2023–25 that weighed on global prices, further gradual supply-side measures from China (>50% of world steel supply) could help rebalance the market and support steel prices in the medium term

Specifically, in mid-May, China released a tougher steel capacity swap plan to curb oversupply. According to the statement of the Ministry of Industry and Information Technology, at least 1.5t of old steel capacity now needs to exit to build ⁠every 1.0t of new capacity nationwide

#steel
Post #2555 119
Morning Bites

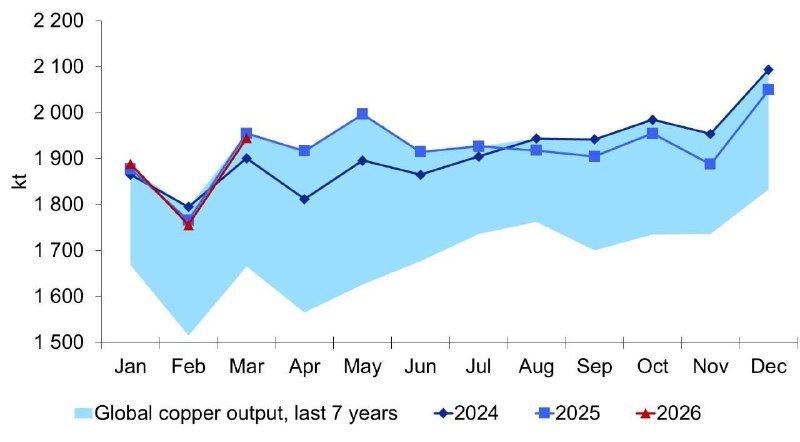
🥉Global mined copper production declined 0.5% YoY in March, matching the revised February dynamics, the ICSG reports. Overall, in 3mo26, global copper output inched down 0.2% YoY. The main contributors to production slowdown were Indonesia and Chile, where mined production declined 42.0% and 5.8% YoY, respectively, affected by major accidents in 2025 and declining ore grades.

Meanwhile, global apparent copper consumption increased 0.8% YoY in 3mo26, though Chinese demand was estimated as broadly flat YoY over the period.

We maintain our bullish view on copper, amid both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2554 127
Morning Bites

🇿🇦South Africa’s PGM mining output jumped 11% YoY in March, vs. the 52% YoY surge in February, per official data. The strong performance in recent months mainly reflects the low base effect from 2025, when heavy rainfalls and maintenance activities disrupted local mining operations. Meanwhile, gold production in the country also increased 17% YoY (vs. the +13% YoY in February)

We expect South African PGM supply to decrease gradually in the long term (e.g. Sibanye's, recently published downbeat guidance for production through 2040)

SA accounts for some 70% of global Pt, 38% of Pd supply and 3% of world gold production

#PGMs #gold
Post #2553 132
Morning Bites (part 2)

🔗Global crude steel output declined 2% YoY in April to 153mnt, after the 4% drop YoY in March, World Steel Association (WSA) data show. China’s production (~50% of global crude steel supply) decreased 3% YoY, while world ex-China output also inched down 1% YoY, per the WSA numbers. Specifically, the data show that Russian and EU output dropped 12% and 2% YoY, respectively, last month, but the US production increased 9% YoY and Indian output (~10% of global steel supply) gained 4% YoY (also up 9% YoY in 4mo26)

Given the ongoing weakness in the global steel market, we believe that Beijing might continue to tighten supply on a gradual basis. Specifically, in mid-May, China’s Ministry of Industry and Information Technology released a tougher steel capacity swap plan to curb oversupply: now at least 1.5t of old steel capacity needs to exit to build ⁠every 1.0t of new capacity nationwide

#steel
  • 👍 1
Post #2552 140
Morning Bites (part 1)

🪨 China has suffered its deadliest coal mine accident since 2009, Bloomberg reports. The gas explosion on Friday night occurred at the 1.2mnt Liushenyu coking coal mine in the Shanxi region, killing at least 82 miners and injuring 128 more. Following the accident, China's coking coal futures prices surged ~8% to ‌hit their daily upper limits

Despite the small size of the Liushenyu mine (~0.2% of local coking coal supply and ~0.4% of global seaborne market), the dramatic nature of the event in terms of casualty numbers has already triggered an intense wave of safety inspections across the entirety of the Shanxi region (~1/3 of China’s total coal supply). In our view, the wide-ranging security checks are likely to provide support both to global coking and thermal prices, especially given seasonally high consumption in the summer and upbeat demand for coal after the escalation of US-Iran conflict

#coal
Post #2550 114
Morning Bites

🏭Global primary aluminium output fell 2.1% YoY in April, after the revised 0.2% YoY gain in March, per International Aluminium Institute (IAI) data. Chinese production (62% of global Al output) grew 1.5% YoY last month; local Al output is capped at 45mnt (China produced 43.4mnt in 2024, and 44.2mnt in 2025, per IAI); in 4mo26, its annualised output was 44.7mnt

Meanwhile, the output of Gulf nations (9% of global Al supply in 2025) shrank 34.7% YoY in April, due to the US-Iran conflict. Specifically, ~60% of the region's Al operations were affected to various extents since late-February (e.g., UAE’s EMAL, Bahrain’s Alba, and Qatar’s Qatalum). Given the nature of the damage, we anticipate sluggish production dynamics in the region until the year’s end

We maintain our view that strong consumption in Asia (including grid), combined with concerns over supply from the Middle East, create upside risks for our Al price forecast, which sees an average USD ~3,100/t in 2026F

#aluminium
Older posts →
Threads Profile ViewerView any public Threads profile without an account.Open ThreadLook →Writing with AI? Make it sound human.Metric37 rewrites AI drafts so they read naturally. Free AI detector, 1,500 words free.Try Metric37 →