TGViewer
Channel Public Channel
Metals Wire

Metals Wire

@metalswire

Global Metals&Mining Research from Glush&Team. No investment advice, just numbers & charts!
Subscribers
693
Photos
2.7K
Videos
1
Links
1.9K
Recent Posts 15 shown
Post #2690 58
Morning Bites

🔗Global crude steel output declined 1.2% YoY to 144.2mnt in August, vs. the broadly flat YoY dynamics seen in July, according to World Steel Association (WSA) data. China’s production (~52% of global crude steel supply) fell 3.7% YoY to 74.6mnt, implying that world ex‑China output grew roughly 1.8% YoY. Specifically, in August, moderate production gains were recorded in India (+4.6% YoY) and the US (+3.0% YoY), while Russia’s output was broadly unchanged (-0.3% YoY), per the WSA data

Given the ongoing weakness in the global steel market, we believe that Beijing might continue to tighten supply on a gradual basis. Specifically, in May, China’s Ministry of Industry and Information Technology released a tougher steel capacity swap plan to curb oversupply: now at least 1.5t of old steel capacity needs to exit to build ⁠every 1.0t of new capacity nationwide

#steel
  • ❤ 1
Post #2688 74
Morning Bites

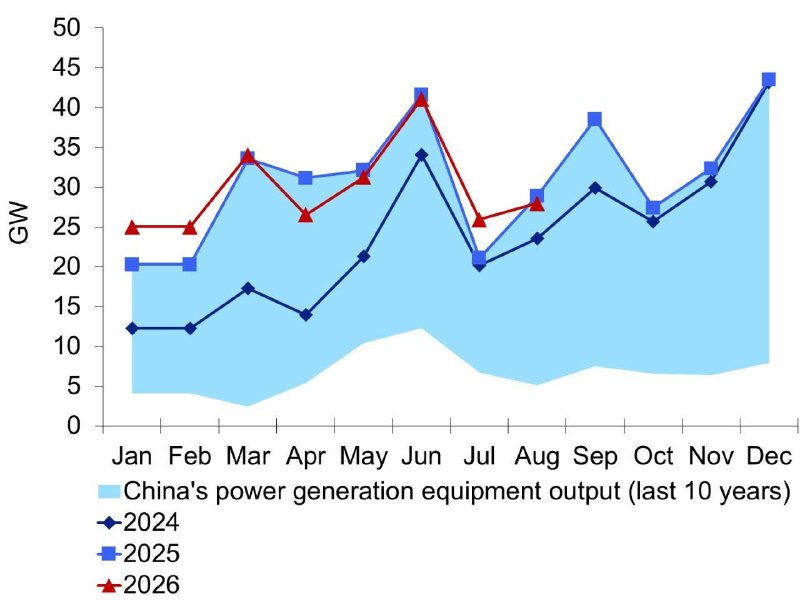
🇨🇳 The output of power generation equipment in China decreased 3% YoY in August, reversing from the 23% YoY increase in July, according to the NBS data. For 8mo26, the figure was still up 3% YoY

📸 Photovoltaic cell output in China declined 18% YoY in August, vs. the 37% YoY drop in July. The local PV cells output also decreased a moderate 8% YoY in 8mo26. Despite the negative dynamics seen recently, the overall production trend remains positive: in July 2026, China released a five-year plan for renewable energy, targeting 2.8TW of solar and wind capacity installed by 2030 (vs. 1.8TW as of end-2025)

Given the solid demand for renewable energy in China, we maintain our positive view on silver, copper and aluminium, which are the key beneficiary metals of the proposed global transition to clean energy in 2026-30

#copper #aluminium #silver
Post #2686 76
Morning Bites

🏭Global primary aluminium output declined 1.7% YoY in August, after the revised drop of 1.6% YoY in July, according to the IAI data. China's supply (63% of global Al output) grew 2.9% YoY last month. Although local Al output of 45.6mnt, annualised, in 8mo26 technically exceeded the cap of 45.0mnt/year (amid utilisation of previously unused quotas, etc), we do not expect the additional volumes to surpass 1.0mnt

Meanwhile, the output of Gulf nations (9% of global Al supply in 2025) shrank 42.6% YoY in August, amid the US-Iran conflict. Specifically, ~60% of the region's Al operations have been affected to various extents since late February (e.g. UAE’s EMAL, Bahrain’s Alba and Qatar’s Qatalum). Hence, we anticipate sluggish production dynamics in the region until at least the end of 2026

We maintain our view that strong consumption dynamics in Asia (including grid), combined with concerns over global supply, are likely to provide support for Al prices, which we forecast will average USD ~3,400/t in 2026F

#aluminium
Post #2684 83
Morning Bites

🇵🇪 Peru’s copper output rose 4% YoY in July, reversing from the 5% YoY decline in June, according to data released by the Energy and Mines Ministry. On a 7mo26 basis, local production was up only 2% YoY, bolstered by stronger output at Antamina, while lower supply from Quellaveco and several other mines limited the overall growth

Meanwhile, the combined copper output of Chile and Peru (~35% of global mined Cu), was down 5% YoY in July. Their joint production remained 4% lower YoY in 7mo26 amid ongoing supply issues in Chile

We maintain our bullish view on copper, amid both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2683 80
Morning Bites (part 2)

🔗CISA mills daily crude steel production in early-September rose to 1.924mnt, up 2.1% from the previous ten days, but 7.8% lower YoY. According to the CISA data, local production declined 5.5% YTD (through 10 September). Meanwhile, local steel inventories increased 1.7% over the period, remaining 4.4% higher YoY

Given the ongoing weakness in the global steel market, we believe that Beijing will continue gradually tightening supply. Although the current five-year plan lacks explicit targets for capacity cuts, China could potentially introduce additional strict supply-control measures, similar to the 2016-17 reform (when >100mnt steelmaking capacity was removed) to accelerate market rebalancing, we believe

For instance, Beijing has recently imposed a more stringent steel capacity swap plan to curb oversupply. Per a Ministry of Industry and Information Technology statement, at least 1.5t of old steel capacity must now be decommissioned to build ⁠every 1.0t of new capacity nationwide

#steel
Post #2682 88
Morning Bites (part 1)

💍Signet has reported 2.2% YoY growth in same-store sales for 2Q26 (May-July), vs. the 1.8% YoY increase in 1Q26. The company has maintained its FY27 (ends in January 2027) total sales guidance, but raised the profit outlook and the lower end of its same-store sales range

Despite the solid downstream demand overall, we maintain our cautious view on the prospects for a global diamond market recovery in 2026-27. The pending sale or spinoff of De Beers by Anglo American leaves the miner’s future strategy and approach to supply discipline uncertain until the transaction has been completed. A sustained market recovery is therefore unlikely before the ownership situation has been resolved, while restoring market discipline and pricing power could take several years

#diamonds
Post #2681 119
Morning Bites

💎India’s natural rough diamond net imports were broadly flat YoY in August, vs. the 10% YoY decline in July, per GJEPC data. Meanwhile, natural polished diamond net exports dropped 11% YoY. Synthetic rough diamond net imports rose 103% YoY, reflecting high monthly volatility in this segment. Lab-grown net rough imports accounted for 15% of total trading in value terms

In our view, the recent escalation of conflict in the Middle East might further weigh on global diamond trading, as it had previously disrupted operations in the UAE and Israel (major hubs), with some auctions being postponed. We maintain our view that it might take time for the global diamond market to recover, especially given risks to supply discipline in 2026-27

India accounts for ~95% of the world's polished stone supply

#diamonds
Post #2680 109
Morning Bites

⛏ Indonesia has sharply cut benchmark prices for its low-grade nickel ore, Bloomberg reports. On 11 September, the local Energy Ministry lowered the "corrective factor" used in its ore-pricing formula to 14% (vs. 26% earlier). Hence, the cost of 1.2% nickel ore will be almost halved effectively

Although the measure contradicts Indonesia's (63% of global Ni supply) previous efforts to monetise its dominant market position, it is likely to ease cost pressure on local HPAL producers (~30% of Indonesia’s nickel output), materially affected by a surge in sulphur prices amid the Middle East conflict

Overall, the measure lowers the risk of near-term HPAL disruptions, which would add some stress to nickel prices (at least in the short term), as the global Ni market remains in significant surplus (~8% of demand in 2025)

#nickel
Post #2678 99
Morning Bites

🇨🇳Total car sales in China were down 5% YoY in August, following broadly flat YoY growth in July

📌Sales of new catalyst-containing (ICE+hybrids) cars in China fell 20% YoY in August (vs. the 15% YoY decline in July). The CPCA attributed the recent drop in ICE car sales to rising fuel costs amid the Middle East conflict. Despite the negative dynamics, we maintain our view that the exclusion of EV support from China’s 2026-30 strategic industries plan, as well as potentially higher PGM loadings into local autocatalysts after 2026 (upcoming China 7 standard), might eventually bolster Pd/Pt fundamentals. To recap, the Chinese automotive sector accounts for 20% and 17% of global Pd and Pt demand, respectively

📌China’s new EV sales were up 18% YoY in August, vs. the 24% YoY gain in July. Local BEV sales (71% of total EV) gained 28% YoY, while PHEVs sales declined 1% YoY

#cars #EV #nickel #lithium #cobalt
Post #2676 107
Morning Bites

🔗China’s crude steel output was down 4% YoY in August, being in line with the dynamics seen in July, per NBS data. On a 8mo26 basis, production was down 3% YoY

Given the continuous contraction of local steel supply (including the 4% YoY decline in 2025, per official data), China’s net steel export volumes have also started to contract gradually in 2026 (-3% YoY in 8mo26), which we believe might foster a normalisation of supplies and lead to a rebound in global steel prices in the medium term. However, if the current dynamic persists and no additional measures are taken, the normalisation process might last through 2026-27 at least

🏢China's property sales declined 15% YoY in August, after the 22% YoY fall in July; they were also 61% lower than in the same month in 2021. Meanwhile, floor space starts dropped a further 30% YoY in August (81% than in 2021). Personal mortgage loans also declined 14% YoY last month (68% lower than 2021), while property completions were down 28% YoY

#steel #property
Post #2675 107
🗞Today, China has published its industrial production data for August (see table above)

#statistics #China
Post #2674 258
Morning Bites

🇿🇦South Africa’s PGM mining output declined 14% YoY in July, following an 8% YoY decrease in June, per official data. Local media report that the negative production dynamics reflected persistent cost pressure, including elevated fuel and energy costs. Meanwhile, gold production in the country also decreased 7% YoY (vs. +6% YoY seen in June)

We expect South African PGM supply to decrease gradually in the long term (e.g. Sibanye recently published downbeat guidance for production through 2040)

In 2025, SA accounted for 71% of global Pt, 34% of Pd mined supply and 3% of world gold production

#PGMs #gold
Post #2673 132
Morning Bites

🚘New car registrations in France, the UK, Spain, Italy and Germany rose 6% YoY in August, vs. the 5% YoY gain in July. Total sales, however, remained below their pre-COVID level (23% lower than August 2019)

Specifically, in France, car sales were 27% beneath their 2019 level, while registrations in Italy and Germany were 22% and 32% lower than in the same month in 2019, respectively. Meanwhile, the UK’s figure increased 2% vs. the August 2019 level, while Spain's was 8% lower

Given these five countries represent more than 70% of new vehicle registrations in Europe in 2025, the region’s car sales likely increased YoY last month, while remaining well below their pre-pandemic levels

#cars #PGMs
Post #2672 148
Morning Bites

📈Gold-backed ETFs bought 121t of gold net in August, after the 23t net purchase in July, per World Gold Council data. The inflows were mainly concentrated in North America (+53t) and Europe (+54t) last month. Meanwhile, since May 2024, global funds have added 1105t net (~11% of world physical gold demand, in annualised terms)

Although, at spot, gold continues to trade far above what we see as its cost support level (the 90%-ile AISC was ~USD 2,600/oz in 2Q26, on our numbers), we expect the precious metal’s price to remain elevated in 2026. Despite the market’s uncertainty around future US Federal reserve monetary decisions (which has been weighing on gold prices recently), we do not expect any meaningful tightening in September, which might improve sentiment on the gold market

#ETF #gold
Post #2671 119
Morning Bites

🏗China’s excavator sales rose 19% YoY in August, including domestic and export deliveries, following a 14% YoY increase in July, per CCMA data. Specifically, domestic sales grew 4% YoY, but remained 35% below July 2021 levels

Although China’s property sector remains in a deep downturn, strong domestic excavators sales (+17% YoY in 8mo26) suggest a moderately positive outlook for a recovery in local construction activity, if the dynamics persist. Meanwhile, Beijing plans further cuts to 'excessive' steel output in 2026 (it was down 3% YoY in 7mo26, after the 4% YoY decline in 2025, per official data). We believe that these two factors might reduce China's surging steel exports, and support global steel prices in the medium term

#steel
Older posts →

About this channel

How can I read @metalswire without a Telegram account?
TGViewer shows the public web preview Telegram publishes for Metals Wire: recent posts, photos, videos and the subscriber count, with no app, login or account.
How many subscribers does Metals Wire have?
Metals Wire (@metalswire) has 693 subscribers on Telegram, refreshed roughly every 30 minutes.
Does Metals Wire know I viewed it here?
No. Public channel previews carry no viewer identity, and TGViewer has no accounts or tracking of what you look up.
Threads Profile ViewerView any public Threads profile without an account.Open ThreadLook →Writing with AI? Make it sound human.Metric37 rewrites AI drafts so they read naturally. Free AI detector, 1,500 words free.Try Metric37 →