Morning Bites
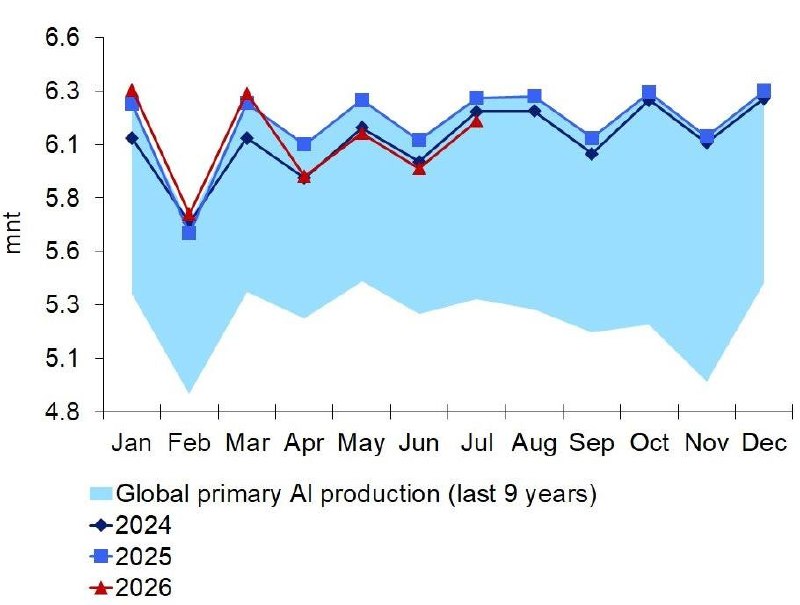
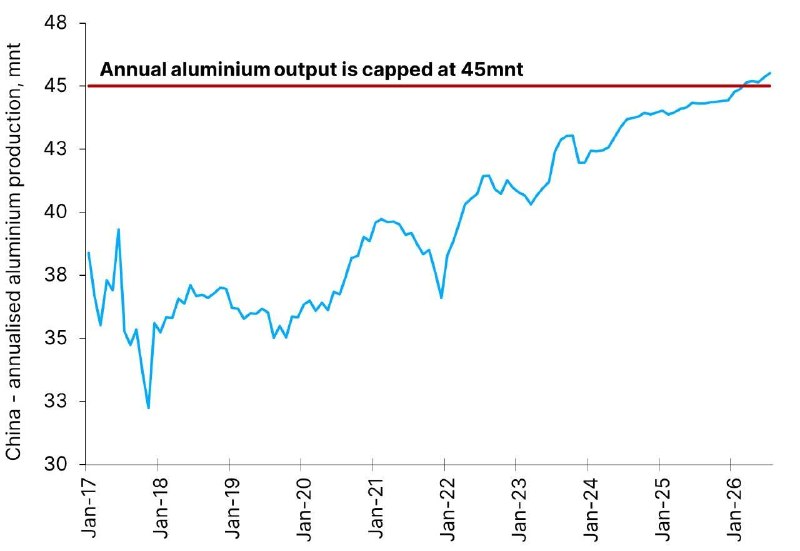
🏭Global primary aluminium output declined 1.7% YoY in July, after the revised drop of 2.1% YoY in June, per IAI data. China's supply (63% of global Al output) grew 2.7% YoY last month. Although local Al output — 45.5mnt annualised in 7mo26 — technically exceeded the cap of 45.0mnt/year (amid utilisation of previously unused quotas, etc), we do not expect the additional volumes to surpass 1.0mnt
Meanwhile, the output of Gulf nations (9% of global Al supply in 2025) shrank 44% YoY in July, amid the US-Iran conflict. Specifically, ~60% of the region's Al operations were affected to various extents since late-February (e.g., UAE’s EMAL, Bahrain’s Alba, and Qatar’s Qatalum). Hence, we anticipate sluggish production dynamics in the region at least until the end-2026
We maintain our view that strong consumption dynamics in Asia (including grid), combined with concerns over global supply, are likely to provide support for the Al price, which we forecast to average USD ~3,400/t in 2026F
#aluminium
Post #2652
131