TGViewer
Channel Public Channel
Metals Wire

Metals Wire

@metalswire

Global Metals&Mining Research from Glush&Team. No investment advice, just numbers & charts!
Subscribers
696
Photos
2.7K
Videos
1
Links
1.9K

Showing posts older than #2550 · Back to latest

Older Posts 17 shown
Post #2549 134
Morning Bites

🔗CISA mills daily crude steel production in early-May was 2.11mnt, up 3.6% from the previous ten days, but 4.3% lower YoY. Per CISA data, local production slid 6.2% YTD (through 10 May). Meanwhile, local steel inventories rose 9.4% over the period, and were 5.1% higher YoY

Given the ongoing weakness in the global steel market, we believe that Beijing will continue to tighten supply on a gradual basis, even though the current five-year plan lacks explicit targets for capacity cuts. After a surge of exports in 2023–25 that weighed on global prices, further gradual supply-side measures from China (>50% of world steel supply) could help rebalance the market and support steel prices in the medium term

Specifically, this week, China released a tougher steel capacity swap plan to curb oversupply. According to the statement of the Ministry of Industry and Information Technology, at least 1.5t of old steel capacity now needs to exit to build ⁠every 1.0t of new capacity nationwide

#steel
Post #2548 150
Morning Bites

💎India’s rough diamond net imports declined 31% YoY in April, vs. the 43% YoY fall in March, per GJEPC data. Meanwhile, polished diamond net exports also dropped 37% YoY. Synthetic rough diamond net imports rose 11% YoY. Lab-grown net rough imports accounted for 12% of total trading in value terms

Rapaport reports that the ongoing conflict in the Middle East has disrupted diamond trading in the UAE and Israel (major hubs), with some auctions being postponed. We maintain our view that it might take time for the global diamond market to recover, especially given risks to supply discipline in 2026

India accounts for ~95% of the world's polished stone supply

#diamonds
Post #2547 133
Morning Bites

📌Johnson Matthey expects a deficit on Pt and surplus on Pd markets in 2026

🚗 According to the annual JM report, global Pt-Pd demand from the automotive sector is set to decline 3-5% YoY, respectively, in 2026, amid lower output of ICE vehicles globally, while jewellery and investment demand are also set to decline this year. In 2025, the automotive sector accounted for 42% of global Pt and 81% of Pd demand

⛏On the supply side, per JM, primary Pt-Pd output is to shrink 2-8% YoY in 2026. The material decline in Pd production is mainly driven by the updated Nornickel guidance

📊 As a result, in 2026 JM sees a 6% deficit on the global Pt market, while Pd is expected to shift into a surplus of 4% (after a 6% deficit in 2025). However, the Pd forecast might be too conservative, in our view, as market participants historically tend to underestimate global Pd demand

#PGMs
Post #2545 116
Morning Bites

🔗China’s crude steel output declined 3% YoY in April, vs. the 6% YoY drop in March, per NBS data. On a 4mo26 basis, production was down 4% YoY

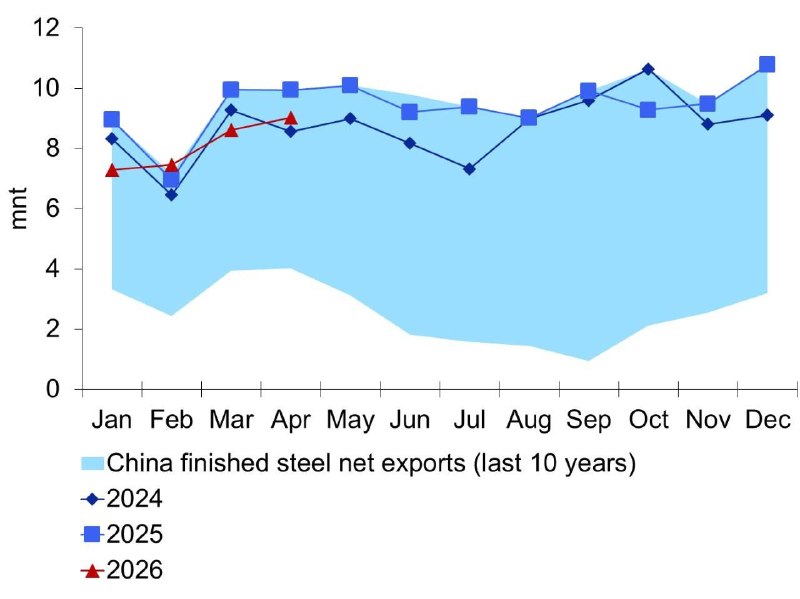
Given the continuous contraction of local steel supply (including -4% YoY in 2025, per official data), Chinese net steel export volumes have also started to decline gradually in early 2026 (-9% YoY in 4mo26), which we believe might bolster normalisation of steel supplies and lead to a rebound in global steel prices in the medium term. However, if the current dynamic persists and no additional measures are taken, normalisation might last through 2026-27

🏢China's property sales decreased 10% YoY in April, after the 8% YoY fall in March; they were also 60% lower than in the same month in 2021. Meanwhile, floor space starts dropped a further 27% YoY in April (-80% vs. 2021). Personal mortgage loans also declined 23% YoY last month (-69% vs. 2021), while property completions were down 19% YoY

#steel #property
Post #2544 123
🗞Today, China has published its industrial production data for April (see table above)

#statistics #China
Post #2543 160
Morning Bites

🏗China’s excavator sales jumped 30% YoY in April
(domestic + export), vs. the +26% YoY in March, per the CCMA data. Specifically, domestic sales were up 35% YoY (but still 59% lower than the same period in 2021). In our view, the sales data provide a mildly bullish indicator of the prospects for a recovery in the local property sector in 2026

The gradual recovery in Chinese excavator sales, recorded since mid-2024, suggests that local construction activity is slowly bottoming out, in our view. Meanwhile, Beijing plans further cuts to 'excessive' steel output in 2026 (-5% YoY in 3mo26, after -4% YoY in 2025, per the official data). We believe that these factors might reduce surging Chinese steel exports, and support global steel prices in the medium term

#steel
Post #2541 127
Morning Bites

🇨🇳Total car sales in China slid 3% YoY in April (vs. the 1% YoY decrease in March)

📌Sales of China’s new catalyst-containing (ICE+hybrids) cars declined 8% YoY in April (vs. the 2% YoY drop in March). We keep our view that the exclusion of EV support from China’s 2026-30 strategic industries plan (as per Reuters), as well as the potentially higher PGM loadings into local autocatalysts after 2026 (due to the upcoming China 7 emissions standard), are likely to bolster Pd/Pt market fundamentals. To recap, the Chinese automotive sector accounts for 20% and 17% of global Pd and Pt demand, respectively

📌China’s new EV sales rose 10% YoY in April, vs. the +1% YoY in March. Specifically, local BEV sales (67% of total EV registrations) rose 10% YoY, while PHEVs gained 9% YoY. Per CnEVpost, overseas markets continued to expand rapidly, with this robust external demand providing a sustained momentum for the overall stability of China's auto industry

#cars #EV #nickel #lithium #cobalt
  • 👍 1
Post #2540 137
Morning Bites

🚘New car registrations in France, the UK, Spain, Italy and Germany rose 8% YoY in April, vs. the 11% YoY gain in March, bolstered by new and revised tax benefits and incentive schemes for EVs in 2026. Total sales, however, remained below their pre-COVID level (16% lower than April 2019)

Specifically, in France, car sales were 26% beneath their 2019 level, while registrations in Italy and Germany were 11% and 20% lower, respectively. The UK figure was 7% less than 2019; Spain's 11% lower

Given these five countries represented more than 70% of new vehicle registrations in Europe in 2025, the region’s car sales likely increased YoY last month, while remaining well below their pre-pandemic levels

#cars #PGMs
  • 🔥 1
Post #2538 118
Morning Bites

🔗China’s net finished steel exports declined 9% YoY in April, vs. the 13% YoY drop in March. On a 4mo26 basis, net exports were also down 9% YoY

Given the ongoing weakness in the global steel market, we believe Beijing might continue to tighten supply on a gradual basis, even though the current five-year plan lacks explicit targets for capacity cuts. After a surge in exports in 2023–25 that weighed on global prices, further gradual supply-side measures from China (>50% of world steel supply) could help rebalance the market and support steel prices in the medium-term

🪨China’s coal imports dropped 13% YoY in April, vs. +1% YoY in March. According to local media, the decline reflected a combination of high seaborne coal prices, lower export supply and solid domestic output

#coal #steel
Post #2537 129
🗞On saturday, China published its preliminary import/export statistics for April (see table above)

#statistics #China
Post #2536 179
Morning Bites

📈Gold-backed ETFs purchased 45t of gold net in April, reversing from the 84t net sale seen in March, per World Gold Council data. We reiterate our view that the massive ETF gold sale in March was driven by the escalation of the Middle East conflict (from 28 February), which triggered a broad risk-off reaction across most asset classes

The inflows were recorded across all regions (mainly in Europe: +27t) last month. Overall, since May 2024, global funds have added 1,053t net (~12% of world physical gold demand, in annualised terms), following the monetary easing cycle in the EU, and US, as well as persisting geopolitical unrest

Although, at spot, gold continues to trade above what we see as its fundamentally reasonable level, we believe that the precious metal’s price will remain elevated in 2026. Moreover, intense inflationary pressure, if high oil prices persist, might eventually trigger a bull-run in gold prices, as happened in 1978-1980

#ETF #gold
Post #2535 151
Morning Bites

💍Hong Kong jewellery and watch sales gained 26% YoY in March, vs. the 24% YoY gain in February, per government data. According to Rapaport, local government expects retail sales to continue their positive trajectory, supported by strong inbound tourism (the number of Mainland visitors was up 20% YoY in 3m26)

However, we maintain our cautious view on the medium-term prospects for a recovery in the global diamond market, given the risks to supply discipline posed by Anglo American's planned sale of De Beers (which is currently disrupting the price-over-volume strategy), as well as geopolitical/trading concerns

#diamonds
Post #2534 133
Morning Bites (part 2)

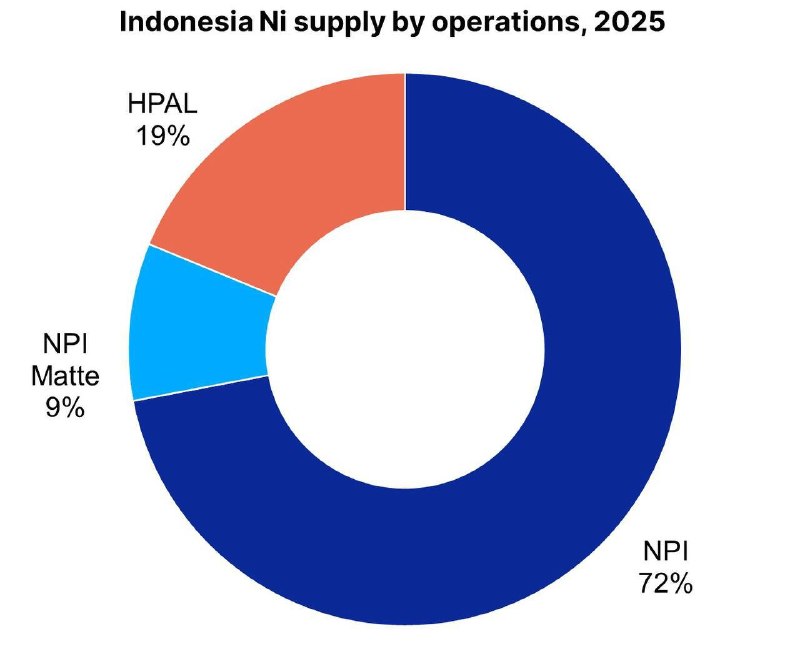
⛏️ Indonesia's Huayou plant has cut Ni output 50% since early May amid surging sulphur costs, SMM reports, citing a company message. The 60kt plant accounts for ~1.5% of global Ni output and uses HPAL technology, which heavily relies on sulphur for acid production. Specifically, HPAL operations accounted for ~20% of Indonesian Ni supply in 2025

While isolated production cuts might offer some support to global Ni prices, they are unlikely to materially rebalance the market in the near term, we believe. To recap, the global Ni market was in a heavy surplus—of 8% of global demand in 2025

#nickel
Post #2533 118
Morning Bites (part 1)

🏦 Global central banks sold net 30t of gold in March, reversing from the 19t net purchases in February, per the World Gold Council's data. This marked the first month of net gold outflows from global central banks since April 2024

Specifically, the major sellers in March were Turkey (60t) and Russia (6t), which offset purchases elsewhere. Quarterly data from the State Oil Fund of Azerbaijan (SOFAZ) also showed net sales of 22t in 1Q26 (which were included in March 2026 statistics)

Although, at spot, gold continues to trade above what we see as its fundamentally reasonable level, we believe that the precious metal’s price will remain elevated in 2026. Moreover, intense inflationary pressure, if high oil prices persist, might eventually trigger a bull-run in gold prices, as happened in 1978-1980. In our view, gold outflows from global ETFs and central banks in early-2026 are likely to be temporary and mainly reflect the risk-off sentiment as the Middle East conflict escalated

#gold
  • 👏 1
Post #2532 129
Morning Bites

🚘US light vehicle sales declined 7% YoY in April, vs. the 12% YoY drop in March. Total car sales in the US were 1% above their pre-Covid (April 2019) level. According to local media reports, the YoY decline was partially driven by soaring fuel costs and the high base effect from 2025 (when sales were boosted ahead of the introduction of tariffs on imported vehicles in early-April 2025)

Meanwhile, the share of catalyst-containing cars in local sales is set to gradually increase, we believe, as US budget legislation eliminated USD 7,500 and USD 4,000 tax credits for buying new and used EVs, respectively, from the end of September 2025. In our view, this factor will further weigh on BEV sales in the US (~8% of global BEV registrations in 2025), as was the case in Germany in early-2024, which is supportive for PGM market fundamentals

On our numbers, North America accounted for 24% and 15% of world autocatalyst Pd and Pt consumption, respectively, in 2024

#cars #PGMs
Post #2531 133
Morning Bites

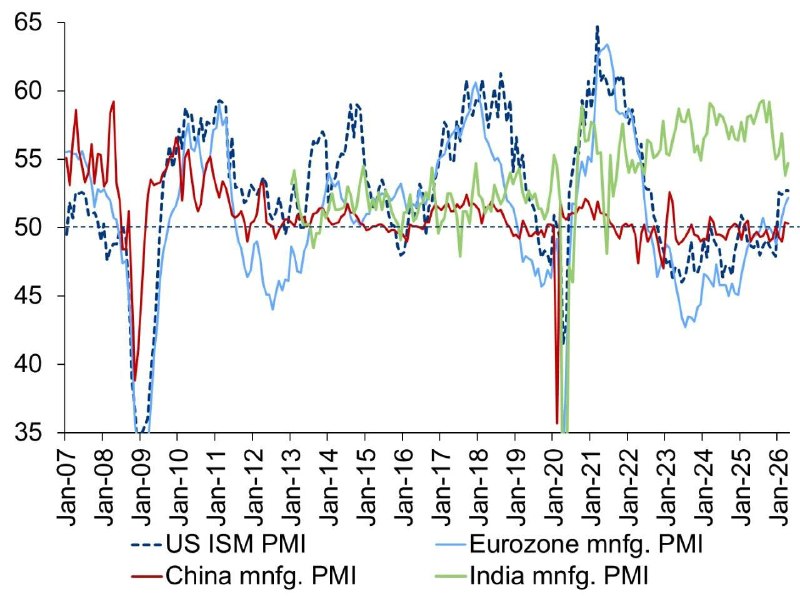
🌏 Global manufacturing PMIs mainly improved in April. The Eurozone Markit Manufacturing PMI printed 52.2 last month (vs. 51.6 in March), while the US ISM Manufacturing PMI remained flat at 52.7 (the highest point since Aug-22)

🇨🇳 The official NBS Manufacturing PMI in China inched down to 50.3 (from 50.4 a month ago). However, the Caixin China Manufacturing PMI jumped to 52.2 (from 50.8 earlier)

🇮🇳 India’s manufacturing PMI of 54.7 remains one of the strongest indicators among the world's key economies

❗️Overall, manufacturing PMI readings in every major region were above 50.0 in April: this could be a positive sign for local industrial metals demand, if the trend persists, we think. At the same time, India remains the standout with continuously robust PMI figures

#PMIs
Post #2530 108
Week ahead data releases in M&M

As the reporting season continues, some global miners are scheduled to release their 1Q26 financials this week. Overall, we are slightly more bullish than the consensus on EBITDA, except for CSN and IAG

We also expect China’s trade statistics for April to be released on Saturday

#reporting_season
Older posts →
Threads Profile ViewerView any public Threads profile without an account.Open ThreadLook →Writing with AI? Make it sound human.Metric37 rewrites AI drafts so they read naturally. Free AI detector, 1,500 words free.Try Metric37 →