TGViewer
Channel Public Channel
Metals Wire

Metals Wire

@metalswire

Global Metals&Mining Research from Glush&Team. No investment advice, just numbers & charts!
Subscribers
696
Photos
2.7K
Videos
1
Links
1.9K

Showing posts older than #2530 · Back to latest

Older Posts 16 shown
Post #2529 166
Morning Bites

🥉Global mined copper production was flat YoY in February, vs. the revised 0.7% increase YoY for January, the International Copper Study Group reports. In 2mo26, copper output inched up 0.4% YoY. The main contributor to production growth in early-2026 was Peru (+2.9% YoY)

Meanwhile, global apparent copper consumption was estimated as unchanged YoY in 2mo26. Specifically, per ICSG data, Chinese apparent demand declined 2% YoY over the period, offsetting world's ex-China increase

We, however, maintain our bullish view on copper, amid both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2528 151
Morning Bites

🏆Global physical gold demand increased 5% YoY to 1,099t in 1Q26 (also being 80% YoY higher in value terms, as gold prices surged 70% YoY in 1Q26), vs. the 13% YoY decline in 4Q25, per World Gold Council data. Specifically, gold jewellery demand dropped 23% YoY in 1Q26, while official central bank purchases were up 3% YoY. Among other key demand segments, robust growth was also recorded in Bars&Coins (+42% YoY)

Despite strong physical purchases, total gold demand was down 9% YoY in 1Q26 in volume terms, as inflows into global ETFs dropped 73% YoY due to the risk-off sentiment among investors as the Middle East conflict escalated. Meanwhile, world mined gold output grew 2% YoY in 1Q26

#gold
Post #2527 128
Morning Bites

🔗CISA mills daily crude steel production in mid-April was 2.11mnt, up 0.3% from the previous ten days, but 5.3% lower YoY. Per CISA data, local production slid 6.2% YTD (through 20 April). Meanwhile, local steel inventories rose 6.4% over the period, and were 11.5% higher YoY

Given the ongoing weakness in the global steel market, we believe Beijing might continue to tighten supply on a gradual basis, even though the current five-year plan lacks explicit targets for capacity cuts. After a surge in exports in 2023–25 that weighed on global prices, further gradual supply-side measures from China (>50% of world steel supply) could help rebalance the market and support steel prices in 2026

Meanwhile, the recent suspension of Iranian steel exports until the end of May might also inject some positivity into steel market sentiment; however, we believe the structural effect on prices will be limited, as Iran accounts only for ~3% of global steel exports

#steel
Post #2525 127
Morning Bites

🇪🇺 Total car sales in the EU rose 4% YoY in 1Q26

🚗💨 Internal combustion engine (ICE) car registrations in Europe decreased 3% YoY in 1Q26, after the 8% YoY drop in 4Q25. Petrol car sales shrank 17% YoY (vs. -18% YoY in 4Q25), while diesel car sales declined 16% YoY. Diesel cars accounted for 23% of total ICE car registrations. Stronger HEV sales (+12% YoY in 1Q26) partially offset the decline in petrol and diesel registrations. Overall, the sales figures remained weak, compared with pre-Covid levels. We note that the EU represents 23% and 30% of global Pd and Pt autocatalyst demand, respectively

🚘 EV sales in Europe rose 28% YoY in 1Q26, after the +40% YoY in 4Q25. Specifically, BEV sales were up 26% YoY (vs. +41% YoY in 4Q25), while PHEV sales surged 33% YoY. The share of BEVs in total EV sales inched down to 67% (vs. 69% in 4Q25)

#cars #EV #nickel #lithium #cobalt
Post #2524 136
Week ahead data releases in M&M

As the reporting season is gaining momentum, several major M&M names are scheduled to release their 1Q26 financials this week. Overall, we are slightly more bullish than the consensus on the miners’ EBITDA, except for Warrior

#reporting_season
Post #2523 159
Morning Bites

🔗Global crude steel output declined 4% YoY in March to 160mnt, after the 2% drop YoY in February, World Steel Association (WSA) data show. China’s production (~50% of global crude steel supply) decreased 6% YoY, while world ex-China output also inched down 2% YoY, per the WSA numbers. Specifically, the data show that Russian and EU output dropped 11% and 5% YoY, respectively, last month, but that US production increased 5% YoY and Indian output (~10% of global steel supply) gained 9% YoY (also up 11% YoY in 3mo26)

Given the ongoing weakness in the global steel market, we believe Beijing might continue to tighten supply on a gradual basis, even though the current five-year plan does not contain explicit targets for capacity cuts. After surging exports in 2023–25 weighed on global prices, further gradual supply-side measures could help rebalance the market and support steel prices in 2026

#steel
Post #2522 138
Morning Bites

🚘EU + UK passenger car registrations rose 11% YoY in March, vs. the 2% YoY drop in February, per the ACEA data, being in-line with preliminary estimates. The overall figure was still 11% lower than the pre-Covid level (March 2019). Specifically, local catalyst-containing car sales grew 5% YoY, while BEV registrations surged 41% YoY last month

In our view, PGM supply issues (e.g., recent SBSW guidance until 2040), cancellation of EV-support programmes in the US (from late-September 2025), as well as potentially higher PGM autocatalyst loadings in China in the coming years (due to planned China 7 emissions standard), might bolster Pd/Pt market fundamentals in the medium term, we believe. Moreover, inflationary pressure, if high oil prices persist, might eventually trigger a bull-run in precious metals prices

In 2024, the EU+UK accounted for some 23% and 26% of world autocatalyst Pd and Pt demand, respectively

#cars
Post #2521 161
Morning Bites

🔗CISA mills daily crude steel production in early-April was 2.08mnt, up 4.2% from the previous ten days, but 5.5% lower YoY. Per CISA data, local production slid 6.4% YTD (through 10 April). Meanwhile, local steel inventories rose 5.8% over the period, and were 9.2% higher YoY

Given the ongoing weakness in the global steel market, we believe Beijing might continue to tighten supply on a gradual basis, even though the current five-year plan lacks explicit targets for capacity cuts. After a surge in exports in 2023–25 that weighed on global prices, further gradual supply-side measures could help rebalance the market and support steel prices in 2026

China accounts for >50% of global steel supply

#steel
Post #2519 139
Morning Bites

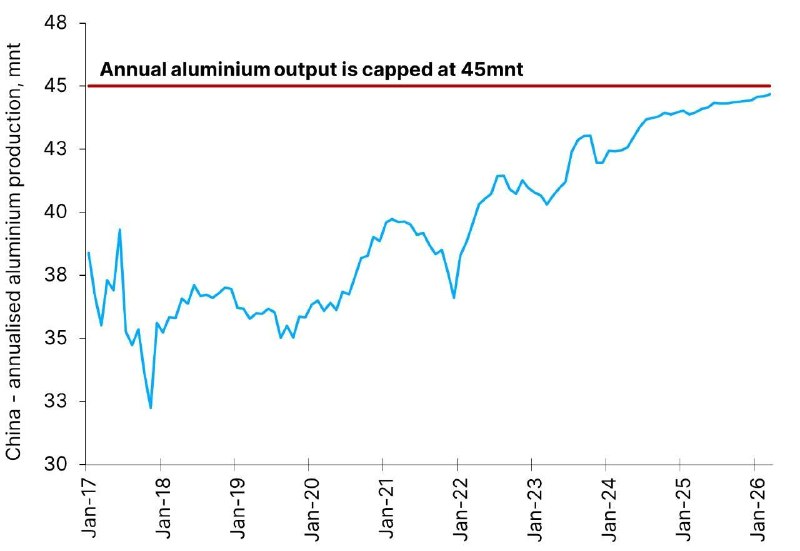
🏭Global primary aluminium output rose 1.0% YoY in March, after the 1.4% YoY gain in February, per International Aluminium Institute (IAI) data. Chinese production (60% of global Al output) grew 1.6% YoY last month. We note that there is limited potential for additional supply growth in China, as local Al output is capped at 45mnt (China produced 43.4mnt in 2024, and 44.2mnt in 2025, per IAI data); in 3mo26, its annualised output was 44.6mnt

The Middle East (9% of global Al supply) is becoming a key upside risk factor for the aluminium market. Specifically, ~60% of the region's Al operations have been affected since the onset of the conflict (e.g., UAE’s EMAL, Bahrain’s Alba, and Qatar’s Qatalum)

We maintain our view that strong consumption dynamics in Asia (including grid), combined with rising concerns about supply from the Middle East, create upside risks for our aluminium price forecast, which sees an average USD ~3,100/t in 2026F

#aluminium
Post #2518 151
Morning Bites

💎India’s rough diamond net imports declined 43% YoY in March, a reversal from the 8% YoY gain in February, per GJEPC data. Meanwhile, polished diamond net exports also dropped 43% YoY. Synthetic rough diamond net imports jumped 33% YoY. Lab-grown net rough imports accounted for 10% of total trading in value terms

Rapaport reports that the ongoing conflict in the Middle East has disrupted diamond trading in the UAE and Israel (major hubs), with some auctions being postponed. We maintain our view that it might take time for the global diamond market to recover, especially given risks to supply discipline in 2026

India accounts for ~95% of the world's polished stone supply

#diamonds
  • 👍 1
Post #2517 141
Week ahead data releases in M&M

As the reporting season is gaining momentum, copper miners are scheduled to release their 1Q26 financials this week. Overall, we are slightly more bullish than the consensus on the Teck’s EBITDA

We also expect EU car registrations and global steel production data to be released on Thursday

#reporting_season
Post #2516 181
Morning Bites

🇿🇦South Africa’s PGM mining output surged 52% YoY in February, vs. the 11% YoY decline in January, per official data. Local media report that the strong performance was mainly attributable to the low base effect from February 2025 (-24% YoY), when heavy rainfalls and maintenance activities disrupted mining operations. Meanwhile, gold production in the country also increased, 13% YoY (vs. the +1% YoY in January)

We expect South African PGM supply to decrease gradually in the long term (e.g. Sibanye's, recently published downbeat guidance for production through 2040)

SA accounts for some 70% of global Pt, 38% of Pd supply and 3% of world gold production

#PGMs #gold
Post #2514 147
Morning Bites

🔗China’s crude steel output declined 6% YoY in March, accelerating from the 4% YoY drop in January-February, per NBS data. On a 3mo26 basis, production was down 5% YoY

Given the continuous contraction of local steel supply (also -4% YoY in 2025, per official data), Chinese net steel export volumes have also started to decline gradually in early 2026 (-10% YoY in 3mo26), which we believe might trigger a rebound in global steel prices, if the dynamic persists

🏢China's property sales decreased 23% YoY in March, after the 14% YoY fall in January-February; they were also 45% lower than in the same month in 2021. Meanwhile, floor space starts dropped a further 12% YoY in March (-72% vs. 2021). Personal mortgage loans also declined 28% YoY last month (-63% vs. 2021), while property completions were down 20% YoY

#steel #property
Post #2513 141
🗞Today, China has published its industrial production data for March (see table above)

#statistics #China
Post #2512 173
Morning Bites

💍LVMH's organic sales of watches and jewellery rose 7% YoY in 1Q26, vs. the 8% YoY gain in 4Q25, a company press-release revealed. LVMH noted solid performance in its jewellery segment, but highlighted risks to the business environment amid escalation of the Middle East conflict

We maintain our cautious view on the prospects for global diamond market recovery in 2026. Risks to supply discipline persist as Anglo American is disrupting the price-over-volume strategy amid the planned sale or spinoff of De Beers. Meanwhile, geopolitical/trading concerns have the potential to disrupt trade and negatively affect consumer sentiment

#diamonds
Post #2510 147
Morning Bites

🔗China’s net finished steel exports declined 13% YoY in March, vs. the 7% YoY drop in 2mo26. On a 3mo26 basis, net exports slid 10% YoY. In our view, Beijing's recent introduction of an export licence requirement for steel shipments from 2026 could have an effect on volumes. Although China aims to further reduce “excessive” steel output in 2026 (which was also -4% YoY in 2025) and strictly prohibits new capacity additions, exports (which increased 25% YoY in 2024 and 8% YoY in 2025) remain close to historical highs. Even though the current five-year plan lacks explicit targets for capacity cuts, further gradual supply-side measures could help rebalance the market and support steel prices, we believe

🪨China’s coal imports inched up 1% YoY in March, remaining in-line with January-February’s dynamic. The China Coal Transportation and Distribution Association (CCTD) expects local coal imports to decline 5% YoY 465mnt in 2026, given the upcoming supply restrictions in Indonesia

#coal #steel
Older posts →
Threads Profile ViewerView any public Threads profile without an account.Open ThreadLook →Writing with AI? Make it sound human.Metric37 rewrites AI drafts so they read naturally. Free AI detector, 1,500 words free.Try Metric37 →