TGViewer
Channel Public Channel
Metals Wire

Metals Wire

@metalswire

Global Metals&Mining Research from Glush&Team. No investment advice, just numbers & charts!
Subscribers
695
Photos
2.7K
Videos
1
Links
1.9K

Showing posts older than #2489 · Back to latest

Older Posts 15 shown
Post #2486 137
Morning Bites

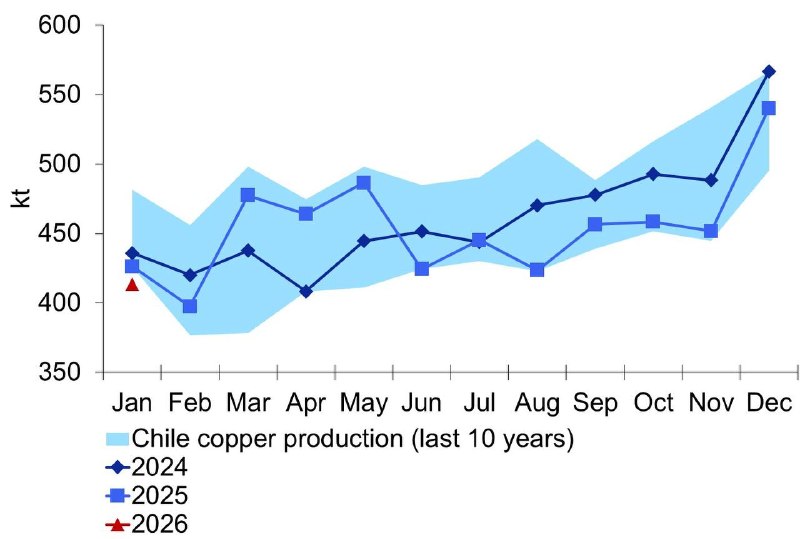
🇨🇱Chile’s copper output dropped 3% YoY in January, after a 5% YoY decrease in December, per the INE data. Chile (~24% of global mined Cu supply) has recently revised down its medium-term Cu production forecast. Specifically, its outlook for 2026 is now 6% below the previous estimate (implying only moderate YoY growth of 2-3%). The revision came amid falling ore grades and adjustments to mining plans in Chile

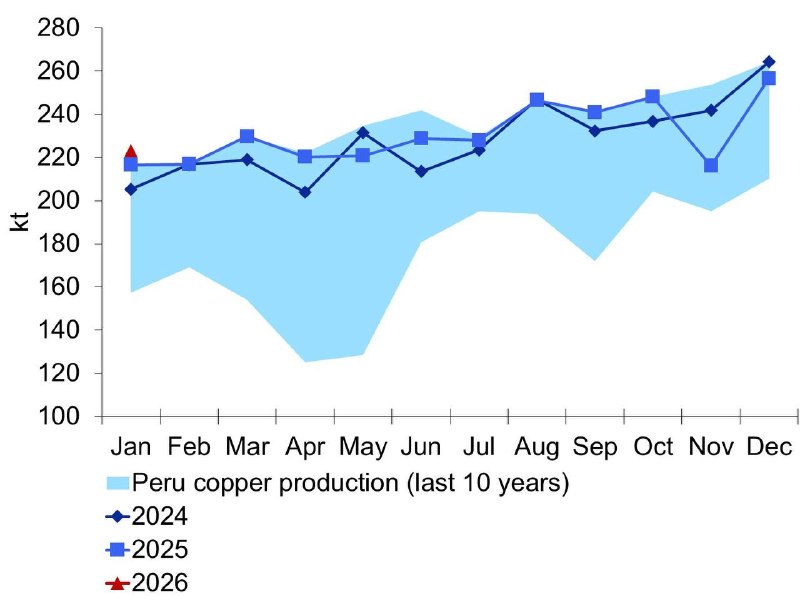
🇵🇪 Peru’s copper output rose 3% YoY in January, vs. the 3% YoY decline in December. Expansion of Antamina will drive up the output in 2026; however, MINEM expects supply of 2.8mnt this year — broadly flat YoY

The joint production of Chile and Peru (>35% of global Cu supply) was down 1% YoY in January

#copper
Post #2484 140
Morning Bites

🏭Global primary aluminium output rose 0.9% YoY in February, after the 1.2% YoY gain in January, per International Aluminium Institute (IAI) data. Chinese production (60% of global Al output) grew 1.6% YoY last month. We note that there is limited potential for additional supply growth in China, as local Al output is capped at 45mnt (China produced 43.4mnt in 2024, and 44.2mnt in 2025, per IAI data); in 2mo26, annualised output was 44.6mnt

Middle East (9% of global Al supply) is becoming a key risk factor for the aluminium market. While no major production shutdowns have been confirmed so far, disruptions are emerging: Aluminium Bahrain has declared force majeure on exports, while Qatar’s Qatalum might halt production amid gas availability issues

We maintain our view that strong consumption dynamics in Asia (including grid), combined with rising geopolitical risks in the Middle East, create upside risks for aluminium prices, which we forecast to average USD ~3,100/t in 2026F

#aluminium
Post #2483 160
Morning Bites

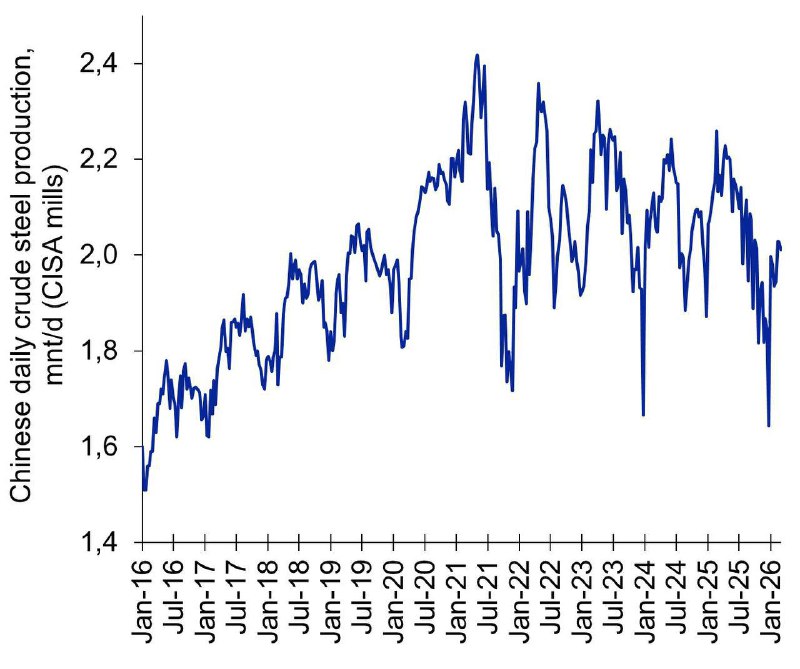
🔗CISA mills daily crude steel production in early-March was 2.01mnt, down 0.8% from the previous ten days and also 5.7% lower YoY. Per CISA data, local production slid 6.6% YTD (through March-10). Meanwhile, local steel inventories rose 2.7% over the period, and were 9.7% higher YoY

In our view, given the ongoing crisis on the global steel market, Beijing might introduce additional strict supply-control measures similar to the 2016-17 reform (when >100mnt of steelmaking capacities was removed). The new reform, if announced, could trigger a recovery in global steel prices in 2026, in our view

China accounts for >50% of global steel supply

#steel
Post #2482 149
Morning Bites

💎India’s rough diamond net imports rose 8% YoY in February, reversing from the 14% YoY decline in January, per GJEPC data. Meanwhile, polished diamond net exports were flat YoY. Synthetic rough diamond net imports jumped 59% YoY (mainly due to the low base effect). Lab-grown net rough imports accounted for 10% of total trading in value terms

According to Rapaport, the ongoing conflict in the Middle East has disrupted diamond trading in the UAE and Israel (major hubs), with some auctions being postponed. We maintain our view that it might take time for the global diamond market to recover, especially given risks to supply discipline in 2026

India accounts for ~95% of the world's polished stone supply

#diamonds
Post #2481 135
Morning Bites

🇿🇦South Africa’s PGM mining output jumped 11% YoY in January, reversing from the 7% YoY decline in December, per official data. Meanwhile, local gold production also inched up 1% YoY (vs. the +2% YoY in December)

We expect local PGM supply to contract gradually in the long-run (e.g., recently published downbeat Sibanye’s production guidance until 2040)

SA accounts for some 70% of global Pt, 38% of Pd supply and 3% of world gold production

#PGMs #gold
Post #2480 142
Morning Bites

🚘US light vehicle sales fell 2% YoY in February, vs. the flat YoY dynamics seen in January. Total car sales in the US were also 8% below their pre-Covid (February 2019) level

Meanwhile, the share of catalyst-containing cars in local sales is to gradually increase, we believe, as new US budget legislation eliminated USD 7,500 and USD 4,000 tax credits for buying new and used EVs, respectively, from the end of September 2025. In our view, this factor will further weigh on BEV sales in the US (~10% of global EV registrations in 2024), as was the case in Germany in early-2024 - supportive for PGM market fundamentals

On our numbers, North America accounted for 24% and 15% of world autocatalyst Pd and Pt consumption, respectively, in 2024
    
#cars #PGMs
Post #2479 158
Morning Bites (part 2)

🇨🇳The State Grid of China increased capital expenditures 81% YoY in January-February 2026, Bloomberg reports, citing a company statement. The numbers underscore Beijing’s push to ease transmission bottlenecks and the State Grid’s overall plan to boost capex 40% in 2026-30 (vs. the average 2021-25 level)

To recap, the State Grid corp. controls ~80% of Chinese electricity transmission capacity and historically accounts for 80-85% of the local grid capital expenditures

On our numbers, the grid accounts for 10-15% of Al and Cu demand in China, so upbeat investments (due to the growing installations of renewable energy) are fundamentally supportive of demand for these base metals. The January-February data are not necessarily representative for the full year, given how seasonally low they tend to be; however, the strong start suggests potential upside risks to our current demand forecasts

#copper #aluminium
Post #2477 125
Morning Bites (part 1)

🔗China’s crude steel output declined 4% YoY in January-February, vs. the 10% YoY drop seen in December, per NBS data. Despite the continuous contraction of local crude steel supply (also -4% YoY in 2025, per official data), Chinese net steel export volumes remain at elevated levels, weighing on global steel prices

Given the prolonged crisis on the global steel market, Beijing might introduce additional supply control measures similar to those imposed in 2016-17, we believe. Beijing has already strictly prohibited new capacity additions in 2026

🏢China's property sales decreased 14% YoY in January-February, after the 17% YoY fall in December; they were also 46% lower than in the same month in 2021. Meanwhile, floor space starts dropped a further 23% YoY in 2mo26 (-70% vs. 2021). Personal mortgage loans also declined 42% YoY last two months (-77% vs. 2021), while property completions were down 28% YoY

#steel #property
Post #2476 109
🗞Today, China has published its industrial production data for January-February (see table above)

#statistics #China
Post #2474 140
Morning Bites

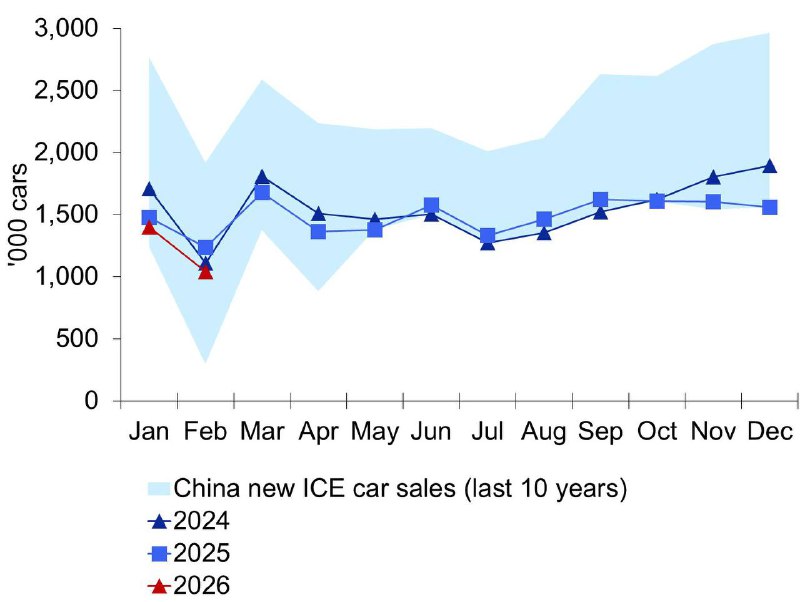
🇨🇳Total car sales in China declined 15% YoY in February (vs. a 3% YoY decrease in January)

📌China’s new catalyst-containing (ICE+hybrids) car sales dropped 17% YoY in February (vs. a 5% YoY reduction in January), which is at least partly associated with the later start of the Lunar New Year in 2026. We reiterate our view that the exclusion of EV support from China’s 2026-30 strategic industries plan (as recently reported by Reuters), as well as the potentially higher PGM loadings into local autocatalysts after 2026 (due to the upcoming China 7 emissions standard), are likely to bolster Pd/Pt market fundamentals in the medium term. To recap, the Chinese automotive sector accounts for 20% and 17% of global Pd and Pt demand, respectively

📌New EV sales in China declined 14% YoY in February, vs. flat YoY dynamics in January. Specifically, local BEV sales (63% of total EV registrations) fell 11% YoY, while PHEVs shrank 20% YoY

#cars #EV #nickel #lithium #cobalt
Post #2473 140
Morning Bites

🚘New car registrations in France, the UK, Spain, Italy and Germany rose 3% YoY in February, vs. the 1% YoY decline in January. Total sales also remained below their pre-COVID level (18% lower than February 2019). Specifically, in France, car sales were 43% beneath their 2019 level, while registrations in Spain and Germany were 8% and 25% lower, respectively. UK and Italy figures grew 10% and 12% vs. 2019 levels

Given these five countries represented more than 70% of new vehicle registrations in Europe in 2025, the region’s car sales likely inched up YoY last month, while remaining well below their pre-pandemic levels

#cars #PGMs
Post #2472 140
Morning Bites (part 2)

🏗China’s excavator sales fell 11% YoY in February
(domestic + export), a major reversal from the 50% YoY increase in January, per CCMA data. Specifically, domestic sales were down 42% YoY (also 72% lower than the same period in 2021). In our view, the contraction seen last month might be associated with the later start of the Lunar New Year in 2026. We also remind readers that the upcoming March data is the most seasonally important print for Chinese excavator sales, and might provide insight into the prospects for the local property sector recovery in 2026

The gradual recovery in Chinese excavator sales, recorded since mid-2024, indicates that local construction activity is slowly bottoming out. Meanwhile, Beijing plans to further cut 'excessive' steel output in 2026 (-4% YoY in 2025, per official data). These factors might cool surging Chinese steel exports, and support global steel prices in 2026, in our view

#steel
Post #2471 136
Morning Bites (part 1)

📈Gold-backed ETFs purchased 26t of gold net in February, vs. the +120t net seen in January, per World Gold Council data. The inflows were recorded in all regions except Europe, which sold 13t net last month. Overall, since May 2024, global funds have added 1,089t net (~13% of world physical gold demand, in annualised terms), following the monetary easing cycle in the EU, and US, as well as persisting geopolitical unrest

Although at spot gold continues to trade above the level we see as fundamentally reasonable in the long term, we believe that the precious metal’s price will remain elevated in 2026, given the ongoing inflows into global central banks and ETFs in addition to the global trade related concerns

#ETF #gold
Post #2470 123
Morning Bites (part 2)

🏭Several nickel processing plants in Indonesia halted production after a landslide in mid-February, Bloomberg reports. The incident affected four facilities at the Morowali Industrial Park, jointly accounting for 30% of Indonesia’s HPAL capacity, with their suspension potentially lasting as long as three months

On our numbers, the affected HPAL plants accounted for ~5% of Indonesian Ni supply in 2025 (and ~3% of global production). However, we remind readers that Ni market remains in a significant surplus (~8% of global demand in 2025), so the positive effect on sentiment is likely to be limited, in our view

#nickel
Post #2468 138
Morning Bites (part 1)

🔗China’s net finished steel exports declined 7% YoY in January-February, vs. the 18% YoY gain in December. In our view, Beijing's recent introduction of an export licence requirement for steel shipments from 2026 could have an effect on volumes. We also remind readers that China aims to further cut “excessive” steel output in 2026 and strictly prohibits new capacity additions. In our view, these measures could help to normalise high Chinese net export volumes (which grew 25% YoY in 2024 and 8% YoY in 2025) and support global steel prices in 2026

🪨China’s coal imports inched up 1% YoY in January-February, after the increase of 12% YoY in December. Per the China Coal Transportation and Distribution Association, local coal imports are expected to fall 5% YoY 465mnt in 2026, given the upcoming supply restrictions in Indonesia

#coal #steel
Older posts →
Threads Profile ViewerView any public Threads profile without an account.Open ThreadLook →Writing with AI? Make it sound human.Metric37 rewrites AI drafts so they read naturally. Free AI detector, 1,500 words free.Try Metric37 →