TGViewer
Channel Public Channel
Metals Wire

Metals Wire

@metalswire

Global Metals&Mining Research from Glush&Team. No investment advice, just numbers & charts!
Subscribers
696
Photos
2.7K
Videos
1
Links
1.9K

Showing posts older than #2426 · Back to latest

Older Posts 17 shown
Post #2425 165
Morning Bites (part 2)

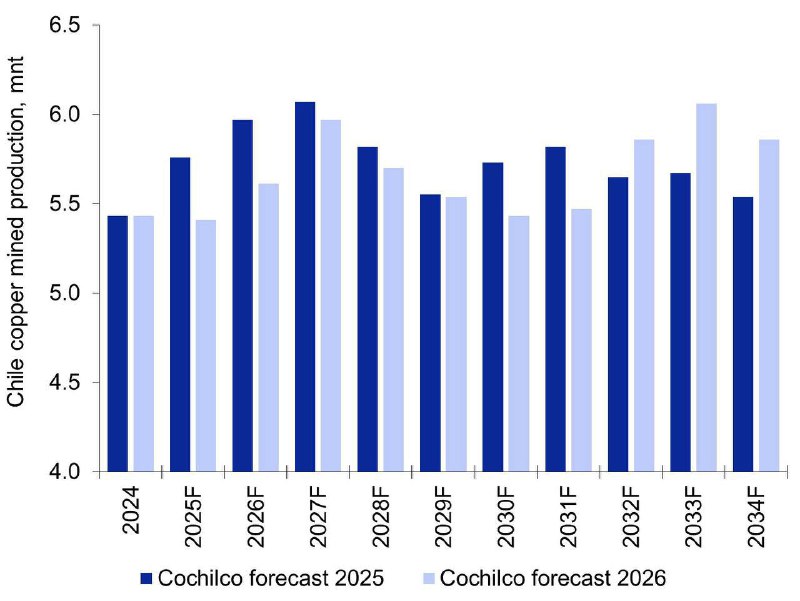
🇨🇱Chile has revised down its medium-term mined copper production outlook for 2026-34, Reuters reports, citing a report from the country's copper commission (Cochilco). Its 2026 copper supply forecast is now 6% below the previous estimate (and, on average, 4% lower for 2026-31). The revision came amid falling ore grades and adjustments to mining plans in Chile (~24% of global mined Cu supply)

To recap, Cochilco also materially cut its production guidance in early-2025, which was, on average, ~15% lower for 2028-34 than its 2023 estimates

We maintain our positive view on copper, amid both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2424 167
Morning Bites (part 1)
 
💍LVMH's organic sales of watches and jewellery rose 8% YoY in 4Q25, vs. the 2% YoY gain in 3Q25, according to a press-release from the retailer. The company noted solid performance of its high end jewellery collections

Despite some improvement in the performance of retailers in 2025, we maintain our cautious view on the prospects for global diamond market recovery (at least in 2026), given the risks to supply discipline related to Anglo American's planned sale of De Beers (which is currently disrupting the price-over-volume strategy), as well as concerns about global trade disputes

#diamonds
Post #2423 142
Morning Bites (part 2)

🚘EU + UK passenger car registrations rose 6% YoY in December, vs. the 1% YoY gain in November, per the ACEA data. Specifically, local catalyst-containing car sales fell 2% YoY, which was offset by the strong BEVs registrations (+41% YoY) last month. However, the overall figure was still 9% lower than the pre-Covid level (December 2019)

We reiterate our view that the ongoing monetary easing cycle in key global economies, the recently announced cancellation of EV-support programmes in the US (from late-September 2025), as well as potentially higher PGM autocatalyst loadings in China in the coming years (due to planned China 7 emissions standard) might bolster Pd/Pt market fundamentals in the medium term

In 2024, the EU+UK accounted for some 23% and 26% of world autocatalyst Pd and Pt demand, respectively

#cars
Post #2422 127
Morning Bites (part 1)

🔗CISA mills daily crude steel production in mid-January was 1.98mnt, down 0.9% from the previous ten days and also 4.5% lower YoY. Meanwhile, local steel inventories rose 7.2% over the period and were 24.7% higher YoY. According to the CISA data, local production slid 3.9% YTD (through January-20)

To recap, in late October, China held a plenum meeting regarding its 2026-30 strategic industries plan (details to be released in March 2026). Given the ongoing crisis on the global steel market, Beijing might introduce additional strict supply-control measures similar to the 2016-17 reform (when >100mnt of steelmaking capacities was removed), we believe. The new reform, if announced, might trigger a recovery in global steel prices in 2026, in our view

China accounts for ~57% of global steel supply

#steel
Post #2421 152
Morning Bites

🔗Global crude steel output declined 4% YoY in December to 140mnt, after the 5% drop YoY in November, per World Steel Association (WSA) data. China’s production (49% of global crude steel supply) decreased 10% YoY (down 4% YoY in 2025), while world ex-China output rose 4% YoY, per WSA estimates. Specifically, the WSA data show that Russian dropped 4% YoY, while EU production gained 4% YoY last month. Meanwhile, US production also increased 4% YoY and Indian output (~10% of global steel supply) gained 10% YoY (also up 10% YoY in 2025)

To recap, in late-October, China held a plenum meeting regarding its 2026-30 strategic industries plan (to be released in March 2026). Given the ongoing crisis on the global steel market, Beijing might introduce additional strict supply-control measures, similar to the 2016-17 reform (when >100mnt steelmaking capacities were removed), we think. A new reform, if announced, could trigger a recovery in global steel prices in 2026

#steel
Post #2420 146
Week ahead data releases in M&M

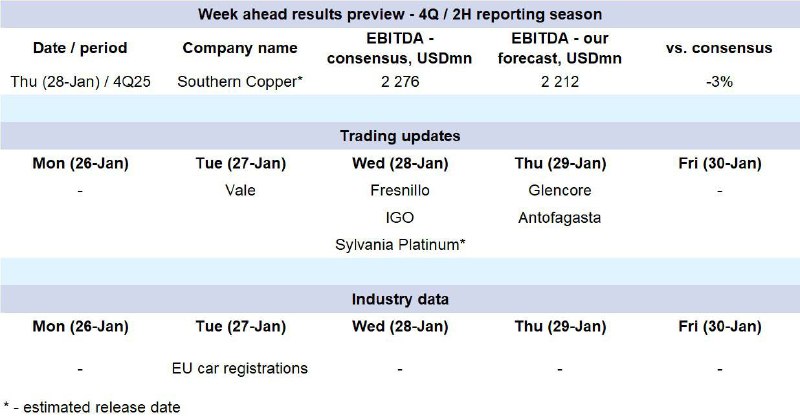
As the reporting season is gaining momentum, only the Southern Copper (SCCO) among the major M&M companies is scheduled to release its 4Q25 financials this week. Overall, we are slightly more conservative than the consensus on the miner's EBITDA

We also expect EU car registrations data for 2025 to be released on Tuesday

#reporting_season
Post #2419 178
Morning Bites

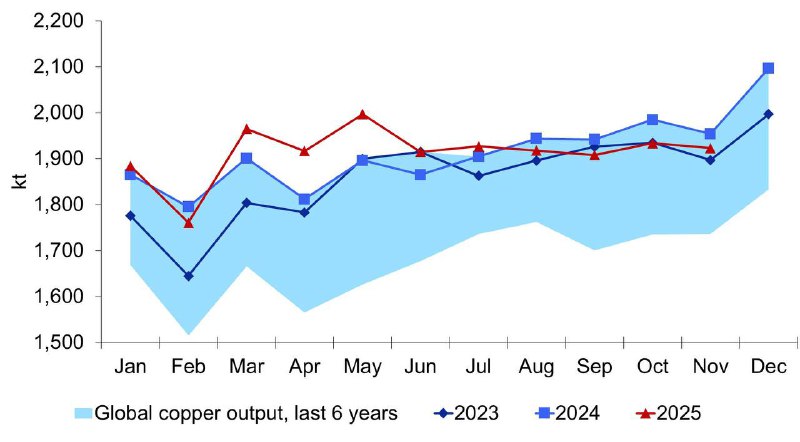
🥉Global mined copper production decreased 1.6% YoY in November, vs. the revised decline of 2.6% YoY in October, the International Copper Study Group reports. On an 11mo25 basis, however, the figure was still up 1.0% YoY, mainly driven by higher output in the DRC (+7% YoY). In our view, the negative production dynamics might persist in the coming months, given the recent accidents and production disruptions at major mines: Grasberg (~3.5% of global supply in 2024), El Teniente (~2.0%) and Kakula (~1.5%)

Meanwhile, apparent consumption dynamics remained positive, up 4.0% YoY in 11mo25, mainly driven by China (+5.5% YoY)

We maintain our bullish view on copper, amid both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2417 140
Morning Bites

🇨🇳Total car sales in China decreased 6% YoY in December (vs. +3% YoY in November)

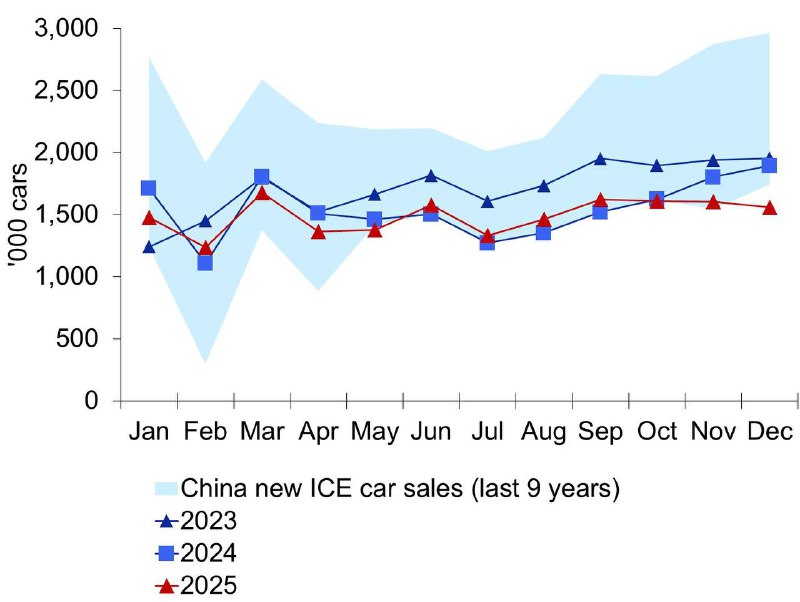
📌China’s new cataIyst containing (ICE+hybrids) car sales dropped 14% YoY in December (vs. -6% YoY in November). However, the exclusion of EV support from China’s 2026-30 strategic industries plan (as recently reported by Reuters), as well as the potentially higher PGM loadings into local autocatalysts after 2026 (due to the upcoming China 7 emissions standard), are likely to bolster Pd/Pt market fundamentals in the medium term. To recap, the Chinese automotive sector accounts for 20% and 17% of global Pd and Pt demand, respectively

📌New EV sales in China increased 7% YoY in December, vs. the +21% YoY in November. Specifically, local BEV sales (65% of total EV registrations) gained 14% YoY, while PHEVs shrank 4% YoY

#cars #EV #nickel #lithium #cobalt
Post #2415 137
Morning Bites (part 2)

🏭Global primary aluminium output inched up 0.5% YoY in December, in line with the dynamics seen November, according to International Aluminium Institute (IAI) data. Chinese production (60% of global Al output) also increased 0.9% YoY last month. Overall, the strong consumption dynamics in Asia (including grid), as well as the ongoing monetary easing cycle in the EU, US and China, are likely to provide further support to Al prices, which we forecast to average USD 3,100/t in 2026F

We also note that there is limited potential for additional supply growth in China, as local Al output is capped at 45mnt (China produced 43.4mnt in 2024, and 44.2mnt in 2025, per IAI data)

#aluminium
Post #2414 150
Morning Bites (part 1)

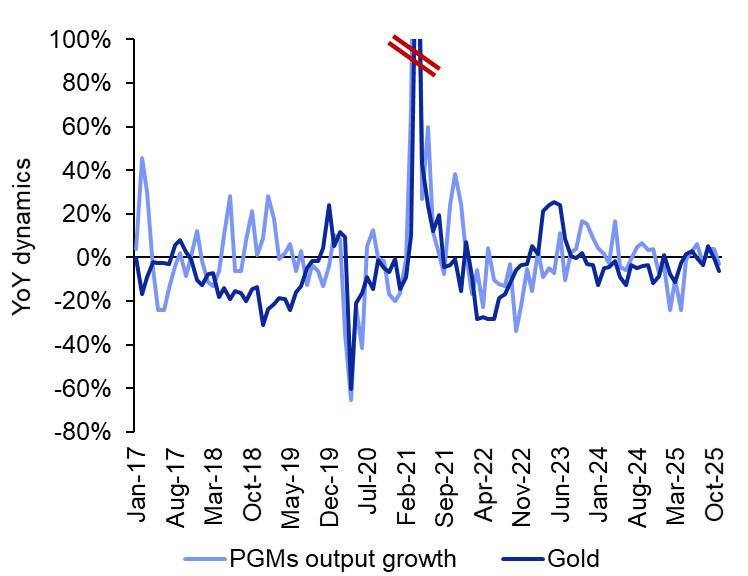
🇿🇦South Africa’s PGM mining output declined 3% YoY in November, reversing from the 4% YoY growth in October, per official data. Meanwhile, local gold production was also down 6% YoY, vs. the broadly flat dynamics of October

Eskom, which controls ~80% of South African electricity supply, has said that it does not expect power cuts until March 2026, unless any major breakdowns occur. We see this as a supportive factor for the future output of South African miners. However, in 11mo25, the country’s PGM production was still down ~4% YoY, which corresponded to some market participants’ estimates that local PGM supply would decrease to ~4.8mnoz in 2025 (vs. ~5.1mnoz last year) amid persisting operational headwinds

SA accounts for ~70% of global Pt, 38% of Pd supply and 3% of world gold production

#PGMs #gold
Post #2413 148
Morning Bites (part 3)

🚘US light vehicle sales inched down 1% YoY in December, vs. the decrease of 7% YoY seen in November. Total car sales were also 6% below their pre-Covid (December 2019) level

To recap, new US budget legislation eliminated USD 7,500 and USD 4,000 tax credits for buying new and used EVs, respectively, from the end of September 2025. In our view, this factor will further weigh on BEV sales in the US (~10% of global EV registrations in 2024), as was the case in Germany in early-2024. Meanwhile, this would be simultaneously supportive for PGM market fundamentals, in our view: the share of catalyst-containing cars in local sales will gradually increase, we believe

On our numbers, North America accounted for 24% and 15% of world autocatalyst Pd and Pt consumption, respectively, in 2024
    
#cars #PGMs
Post #2412 144
Morning Bites (part 2)

💎De Beers has cut prices for its >0.75ct rough diamonds
, marking the first official revision since December 2024, Bloomberg reports. However, the exact scale of the reductions remains unclear, as the company adjusted its rules and assortments, making direct comparisons complicated

In our view, De Beers might have started shifting its previously non-public discounts into regular sales cycles. To recap, since early-2025, the miner has been selling diamonds to selected buyers at closed auctions, while prices at regular tenders remained up to 25% higher. This decision undermined market confidence and disrupted traditional price-over-volume strategy, we believe

We maintain a cautious view on the global diamond market and believe that the supply discipline will not start to recover until Anglo American completes the planned sale (or spin-off) of De Beers, which accounts for ~30% of global rough diamonds mined supply

#diamonds
Post #2411 146
Morning Bites (part 1)

💎India’s rough diamond net imports rose 17% YoY in December, decelerating from the +73% YoY spike in November (mainly due to the low base). Meanwhile, polished diamond net exports fell 8% YoY. Synthetic rough diamond net imports surged 50% YoY. Lab-grown net rough imports accounted for 10% of total trading in value terms

We maintain our view that it might take time for the global diamond market to recover, given risks to supply discipline in 2026, as well as new trading disruptions (the US raised import tariffs on India’s goods to 50% from late-August 2025)

India accounts for ~95% of the world's polished stone supply

#diamonds
Post #2410 151
Morning Bites (part 2)

💍Hong Kong jewellery and watch sales gained 4% YoY in November, vs. the +9% YoY seen in October, per government data. According to Rapaport, the performance was supported by high gold prices and strong inbound tourism (the number of Mainland visitors was up 19% YoY in November)

We maintain our cautious view on the medium-term prospects for a recovery in the global diamond market, given the risks to supply discipline related to Anglo American's planned sale of De Beers (which is currently disrupting the price-over-volume strategy), as well as geopolitical/trading concerns

#diamonds
Post #2408 126
Morning Bites (part 1)

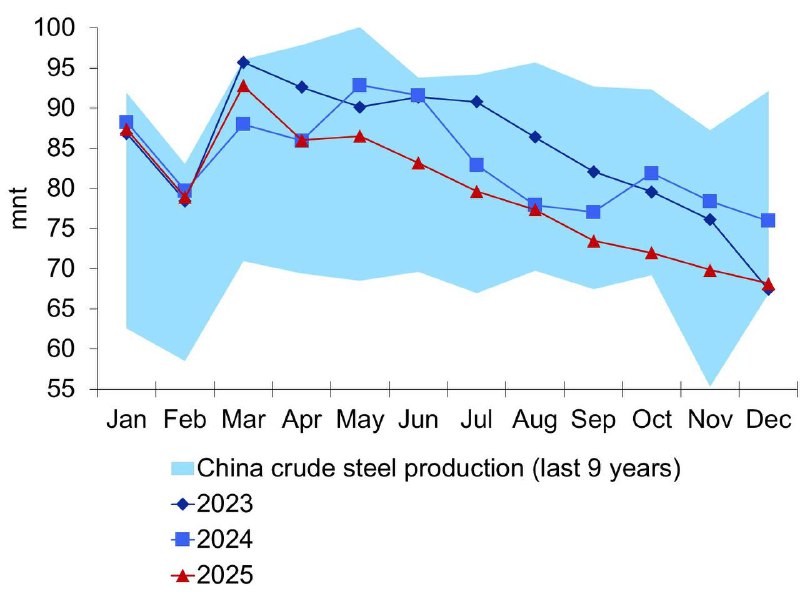
🔗China’s crude steel output declined 10% YoY in December, broadly in-line with the 11% YoY drop in November, per NBS data. Although local crude steel supply dropped 4% YoY in 2025, per official data, China's net steel exports were still up 8% YoY over the period, weighing on global steel prices. The recent production decreases were related to Beijing’s plans to cut 'excessive' steel output in 2025 and strictly prohibit new capacity additions in 2025-26. Given the ongoing crisis in the global steelmaking industry, Beijing might introduce additional supply control similar to the measures it imposed in 2016-17, we believe

🏢China's property sales decreased 17% YoY in December, after the -18% YoY in November; they were also 56% lower than in the same month in 2021. Meanwhile, floor space starts dropped a further 19% YoY in December (-67% vs. 2021). Personal mortgage loans also declined 39% YoY last month (-61% vs. 2021), while property completions were down 18% YoY

#steel #property
Post #2407 146
🗞Today, China has published its industrial production data for December (see table above)

#statistics #China
Post #2406 150
Week ahead data releases in M&M

As the reporting season unfolds, we commence a series of posts devoted to the forthcoming data releases. This week, among major M&M names, Alcoa and Freeport are set to release their 4Q25 earnings. On the EBITDA side, we are more conservative on Freeport’s results (than the consensus), while being slightly more positive on Alcoa's financials

We also await South African PGM production statistics for November this week
 
#reporting_season
Older posts →
Threads Profile ViewerView any public Threads profile without an account.Open ThreadLook →Writing with AI? Make it sound human.Metric37 rewrites AI drafts so they read naturally. Free AI detector, 1,500 words free.Try Metric37 →