TGViewer
Channel Public Channel
Metals Wire

Metals Wire

@metalswire

Global Metals&Mining Research from Glush&Team. No investment advice, just numbers & charts!
Subscribers
695
Photos
2.7K
Videos
1
Links
1.9K

Showing posts older than #2650 · Back to latest

Older Posts 17 shown
Post #2649 122
Morning Bites

💎India’s natural rough diamond net imports fell 10% YoY in July, vs. the 28% YoY decline in June, per GJEPC data. Meanwhile, natural polished diamond net exports dropped 25% YoY. Synthetic rough diamond net imports rose 57% YoY, reflecting high monthly volatility in this segment. Lab-grown net rough imports accounted for 14% of total trading in value terms

In our view, the recent escalation of conflict in the Middle East might further weigh on global diamond trading, as it had previously disrupted operations in the UAE and Israel (major hubs), with some auctions being postponed. We maintain our view that it might take time for the global diamond market to recover, especially given risks to supply discipline in 2026

India accounts for ~95% of the world's polished stone supply

#diamonds
Post #2648 132
Morning Bites

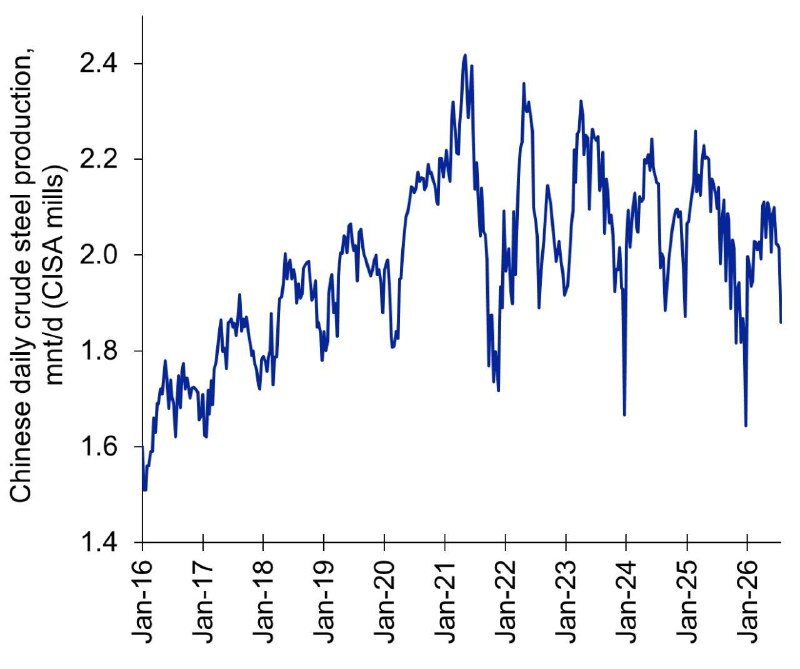
🔗CISA mills daily crude steel production in early-August was 1.973mnt, up 5.8% from the previous ten days, but 4.9% lower YoY. Per CISA data, local production has declined 5.4% YTD (through 10 August). Therefore, local steel inventories increased 5.5% over the period, and were up 14.0% YoY

Given the ongoing weakness in the global steel market, we believe that Beijing will continue to gradually tighten supply. Although the current five-year plan lacks explicit targets for capacity cuts, it is our view that China might also introduce additional strict supply-control measures, similar to the 2016-17 reform (when >100mnt steelmaking capacity was removed)

For instance, Beijing has recently imposed a more stringent steel capacity swap plan to curb oversupply. Per a Ministry of Industry and Information Technology statement, at least 1.5t of old steel capacity must now be decommissioned to build ⁠every 1.0t of new capacity nationwide

#steel
Post #2646 102
Morning Bites (part 2)

🇨🇳Total car sales in China were broadly flat YoY in July, following the 3% YoY decline in June

📌Sales of new catalyst-containing (ICE+hybrids) cars in China fell 15% YoY in July (vs. -18% YoY in June). The CPCA attributed the recent drop in ICE car sales to rising fuel costs amid the Middle East conflict. Despite the negative dynamics, we maintain our view that the exclusion of EV support from China’s 2026-30 strategic industries plan, as well as potentially higher PGM loadings into local autocatalysts after 2026 (upcoming China 7 standard), might eventually bolster Pd/Pt fundamentals. To recap, the Chinese automotive sector accounts for 20% and 17% of global Pd and Pt demand, respectively

📌China’s new EV sales were up 24% YoY in July, matching the 24% YoY gain in June. Local BEV sales (69% of total EV) gained 32% YoY, while PHEVs sales increased 8% YoY

#cars #EV #nickel #lithium #cobalt
Post #2644 90
Morning Bites (part 1)

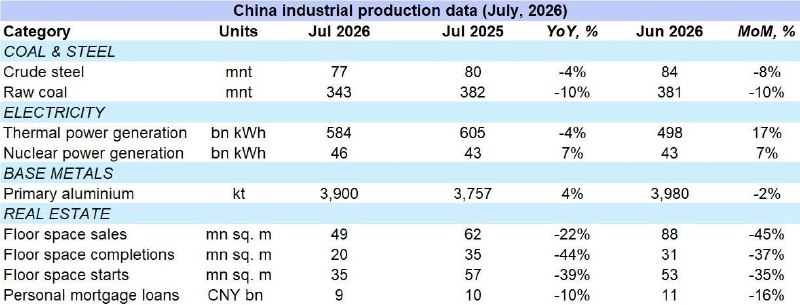
🔗China’s crude steel output was down 4% YoY in July, vs. June's unchanged YoY figure, per NBS data. On a 7mo26 basis, production was down 3% YoY

Given the continuous contraction of local steel supply (including the 4% YoY decline for FY25, per official data), Chinese net steel export volumes have also started to contract gradually in 2026 (4% YoY in 7mo26), which we believe might foster a normalisation of steel supplies and thus lead to a rebound in global steel prices in the medium term. However, if the current dynamic persists and no additional measures are taken, the normalisation process might last through 2026-27 at least

🏢China's property sales declined 22% YoY in July, after the 16% YoY fall in June; they were also 62% lower than in the same month in 2021. Meanwhile, floor space starts dropped a further 39% YoY in July (80% than in 2021). Personal mortgage loans also declined 10% YoY last month (65% lower than 2021), while property completions were down 44% YoY

#steel #property
Post #2643 115
🗞Today, China has published its industrial production data for July (see table above)
      
#statistics #China
Post #2642 121
Week ahead data releases in M&M

The reporting season is drawing to a close, but several major M&M names are still to release their 2Q/1H26 financials. Of those companies reporting this week, we are generally more bullish than the consensus on miners’ EBITDA (except for SQM)

This week is also due to bring
China’s industrial production data for July 2026

#reporting_season
Post #2641 142
Morning Bites

🇿🇦South Africa’s PGM mining output declined 8% YoY in June, following a 4% YoY decrease in May, per official data. According to local media, the negative production dynamics reflected elevated mining costs (including fuel) and a less supportive pricing environment relative to mid-2025. Meanwhile, gold production in the country increased 6% YoY (vs. -4% YoY in May)

We expect South African PGM supply to decrease gradually in the long term (e.g. Sibanye recently published downbeat guidance for production through 2040)

In 2025, SA accounted for 71% of global Pt, 34% of Pd mined supply and 3% of world gold production

#PGMs #gold
Post #2640 145
Morning Bites

🥈Global ETFs bought 5mnoz net of silver in July, following the revised outflows of 11mnoz net seen in June, per funds data. The gain accounted for ~5% of global Ag demand in 2025, in annualised terms, which underpins the elevated price volatility. Overall, in 7mo26, global ETFs sold 78mnoz net (12% of global Ag demand in annualised terms)

In our view, solid demand for renewable energy in China will further support the silver market’s physical deficit (4% of global Ag consumption in 2025) in coming years. Meanwhile, in the medium-term we see ~USD 65/oz as fundamentally reasonable level, but concede that high volatility in Ag prices mainly due to abnormal speculative activity

#silver
Post #2639 125
Morning Bites

🚘New car registrations in France, the UK, Spain, Italy and Germany rose 5% YoY in July, vs. the 12% YoY gain in June. Total sales, however, remained below their pre-COVID level (17% lower than July 2019)

Specifically, in France, car sales were 27% beneath their 2019 level, while registrations in Italy and Germany were 20% and 19% lower than in the same month in 2019, respectively. Meanwhile, the UK’s figure was flat vs. the July 2019 level, while Spain's was 13% lower

Given these five countries represented more than 70% of new vehicle registrations in Europe in 2025, the region’s car sales likely increased YoY last month, while remaining well below their pre-pandemic levels

#cars #PGMs
Post #2638 143
Morning Bites

🏗China’s excavator sales rose 14% YoY in July, including domestic and export deliveries, following a 35% YoY increase in June, per CCMA data. Specifically, domestic sales grew 4% YoY, but remained 38% below July 2021 levels

Although China’s property sector remains in a deep downturn, strong domestic excavators sales (+19% YoY in 7mo26) suggest a moderately positive outlook for a recovery in local construction activity, if the dynamics persist. Meanwhile, Beijing plans further cuts to 'excessive' steel output in 2026 (it was down 3% YoY in 1H26, after the 4% YoY decline in 2025, per official data). We believe that these two factors might reduce China's surging steel exports, and support global steel prices in the medium term

#steel
Post #2637 139
Morning Bites

🔗CISA mills daily crude steel production in late-July was 1.864mnt, down 7.5% from the previous ten days, and 6.0% lower YoY. Per CISA data, local production has declined 5.5% YTD (through 31 July). Meanwhile, local steel inventories also decreased 10.2% over the period, but were still up 10.2% YoY

Given the ongoing weakness in the global steel market, we believe that Beijing will continue to gradually tighten supply. Although the current five-year plan lacks explicit targets for capacity cuts, it is our view that China might also introduce additional strict supply-control measures, similar to the 2016-17 reform (when >100mnt steelmaking capacity was removed)

For instance, Beijing has recently imposed a more stringent steel capacity swap plan to curb oversupply. Per a Ministry of Industry and Information Technology statement, at least 1.5t of old steel capacity must now be decommissioned to build ⁠every 1.0t of new capacity nationwide

#steel
Post #2636 135
Week ahead data releases in M&M

As the reporting season continues, some global M&M names are scheduled to release their 1H/2Q26 financials this week. Our EBITDA forecasts for most of the miners are broadly in line with the consensus, but we are slightly more bullish on MMG’s performance

#reporting_season
Post #2635 147
Morning Bites (part 3)

🇨🇩 The DRC has banned exports of copper and cobalt concentrates, but suggests the restrictions are to be lifted for one year in “special cases”, Reuters reports, citing the official order. Although the measure's duration remains unclear, local authorities imposed similar restrictions in 2013–19 to bolster domestic processing

Currently most of the DRC’s copper ores are already processed locally through SXEW technology into refined copper (not affected by the ban). However, on our numbers, 0.5-0.6mnt of the country’s total 3.6mnt Cu output in 2025 were still exported in concentrate. Hence, the suspension of concentrate exports could further widen the global Cu market deficit, which we forecast to account for ~2% of demand in 2027 in our base case scenario

We maintain our bullish view on copper, amid both short‑ and long‑term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2634 126
Morning Bites (part 2)

📈Gold-backed ETFs purchased 23t of gold net in July, reversing from the 77t net sale in June, per World Gold Council data. The inflows were mainly concentrated in Europe (+17t) and Asia (+5t) last month. Meanwhile, since May 2024, global funds have added 984t net (~10% of world physical gold demand, in annualised terms)

Although, at spot, gold continues to trade far above what we see as its cost support level (the 90%-ile AISC was ~USD 2,450/oz in 1Q26, on our numbers), we expect the precious metal’s price to remain elevated in 2026. Despite the market’s uncertainty around future US Federal reserve monetary decisions (which has been weighing on gold prices recently), we do not expect any meaningful tightening in September, which might improve sentiment on the gold market

#ETF #gold
Post #2632 104
Morning Bites (part 1)

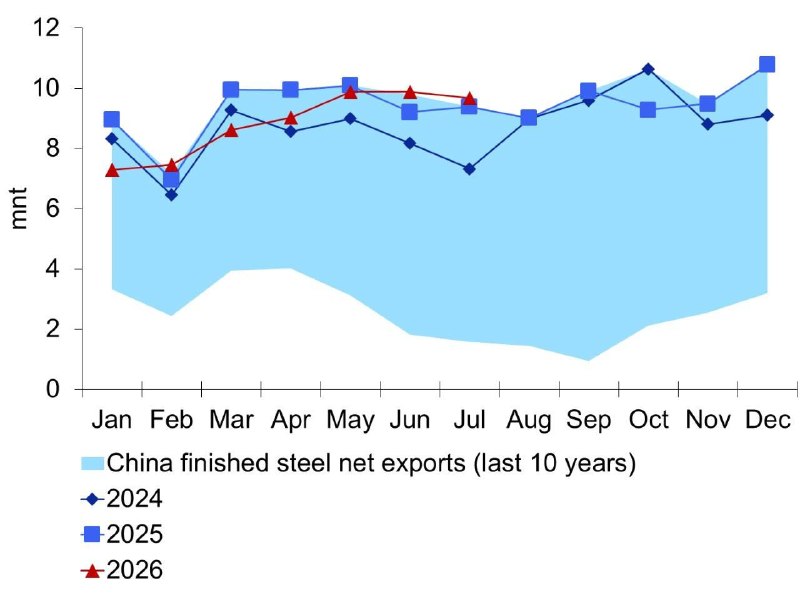
🔗China’s net finished steel exports rose 3% YoY in July, decelerating from the 7% YoY gain in June. On a 7mo26 basis, net exports were still down 4% YoY. Although China aims to further reduce “excessive” steel output in 2026 (which was also 4% lower YoY in 2025) net exports remain close to historical highs (after the 25% and 8% YoY growth in 2024 and 2025, respectively). The current five-year plan lacks explicit targets for capacity cuts; however, we believe that further gradual supply-side measures could help rebalance the market and support steel prices

🪨China’s coal imports jumped 21% YoY in July, remaining at elevated levels, same as in June (+29% YoY). According to Reuters, the dynamics were mainly associated with the dramatic underground accident in late May, which triggered massive security checks across Chinese coal mines

#coal #steel
Post #2631 117
🗞Today, China published its preliminary import/export statistics for July (see table above)

#statistics #China
Post #2630 143
Morning Bites (part 2)

🏦Global central banks purchased 51t (net) of gold in June, vs. the revised 45t (net) in May, according to World Gold Council data. The major buyers in June were Poland (+19t) and China (+15t), which outweighed sales by Russia (-9t) and Turkey (-2t)

Although, at spot, gold continues to trade way above what we see as its cost support level (the 90%-ile AISC was ~USD 2,450/oz in 1Q26, on our numbers), we expect the precious metal’s price to remain elevated in 2026. Furthermore, a recent WGC survey indicates that a record 45% of global central banks plan to increase their gold reserves over the next 12 months

#gold
Older posts →
Threads Profile ViewerView any public Threads profile without an account.Open ThreadLook →Writing with AI? Make it sound human.Metric37 rewrites AI drafts so they read naturally. Free AI detector, 1,500 words free.Try Metric37 →