TGViewer
Channel Public Channel
Metals Wire

Metals Wire

@metalswire

Global Metals&Mining Research from Glush&Team. No investment advice, just numbers & charts!
Subscribers
695
Photos
2.7K
Videos
1
Links
1.9K

Showing posts older than #2630 · Back to latest

Older Posts 18 shown
Post #2629 141
Morning Bites (part 1)

⛏️ Codelco has halted its expansion of the El Teniente copper mine amid new seismic risks, revealed by geotechnical study, Bloomberg reports, citing a company statement. The decision is based on data collected over the past six months, pointing to a seismic phenomenon

Although Codelco has not yet officially announced a timeline, a union leader does not expect the development of the mine’s Andes Norte section to resume before mid-2028, raising concerns over the long‑term mining profile. To recap, a rock collapse at El Tentiente’s (~1.5% of global mined Cu supply in 2025) deep underground levels already caused a fatal accident in mid-2025

We maintain our bullish view on copper, amid both short‑ and long‑term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2628 149
Morning Bites

💍Hong Kong jewellery and watch sales grew 20% YoY in June, vs. the 26% YoY gain in May, per government data. According to Rapaport, local sales growth was supported by the ongoing economic expansion, rising local incomes and a steady increase in inbound tourism (the number of Mainland visitors was up 16% YoY in 1H26), as well as stronger consumer confidence

However, we maintain our cautious view on the prospects for a global diamond market recovery in 2026. Risks to supply discipline remain, as Anglo American's planned sale or spinoff of De Beers undermines market participants' confidence in the price-over-volume strategy. Meanwhile, geopolitical concerns keep weighing on consumer sentiment

#diamonds
Post #2626 116
Morning Bites (part 2)

🇪🇺 Total car sales in the EU rose 8% YoY in 2Q26

🚗💨 Internal combustion engine (ICE) car registrations in Europe fell 2% YoY in 2Q26, followng the 3% YoY decline in 1Q26. Petrol car sales dropped 16% YoY (vs. -17% YoY in 1Q26), while diesel car sales slid 17% YoY. Diesel cars accounted for 23% of total ICE car registrations. Stronger HEV sales (+13% YoY in 2Q26) partially offset the contraction in petrol and diesel registrations. Overall, the sales figures remained subdued compared with pre-Covid levels. We note that the EU represented 23% and 25% of global Pd and Pt autocatalyst demand in 2025, respectively

🚘 EV sales in Europe jumped 35% YoY in 2Q26, after the +28% YoY in 1Q26. Specifically, BEV sales surged 43% YoY (vs. +26% YoY in 1Q26), while PHEV sales were up 20% YoY. The share of BEVs in total EV sales rose to 70% (vs. 67% in 1Q26)

#cars #EV #nickel #lithium #cobalt
Post #2625 111
Morning Bites (part 1)

🌏 Global manufacturing PMIs showed mixed dynamics in July. The Eurozone Markit Manufacturing PMI came in at 51.9 (vs. 51.4 in June), while the US ISM Manufacturing PMI jumped to 55.6 (vs. 53.3 earlier), reflecting stronger output amid solid demand, resilient investments (including AI‑related capex) and still low inventories

🇨🇳 The official NBS Manufacturing PMI in China, however, edged down to 49.2 (from 50.3 a month ago). The Caixin China Manufacturing PMI also declined to 50.9 (vs. 51.7 earlier)

🇮🇳 India’s manufacturing 53.5 remains one of the strongest indicators among the key global economies

❗️Overall, manufacturing PMI readings in western economies remained above 50.0, which could be a positive sign for local industrial metals demand, if the trend persists, we think. At the same time, Chinese PMIs showed rather weak dynamics, while India is the standout with continuously robust PMI figures

#PMIs
Post #2624 121
Morning Bites

🇨🇱Chile’s copper output increased 5% YoY in June, vs. the 13% YoY decline in May, mainly due to the low base effect, per the INE data. On a 1H26 basis, output was still down 7% YoY, affected by ongoing grade depletion and other operating challenges. Meanwhile, heavy snowfalls in late-July interrupted mining operations at some Chilean mines, which is likely to add more pressure to copper supply

Considering the negative dynamics in Chilean production (~24% of global mined Cu supply), Cochilco has revised its 2026 production forecast down to 5.3mnt (-2% YoY), from 5.6mnt previously (+4% YoY). The 5.5mnt supply outlook for 2027 is also 8% lower than the previous estimate

We maintain our bullish view on copper, amid both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2623 107
Week ahead data releases in M&M

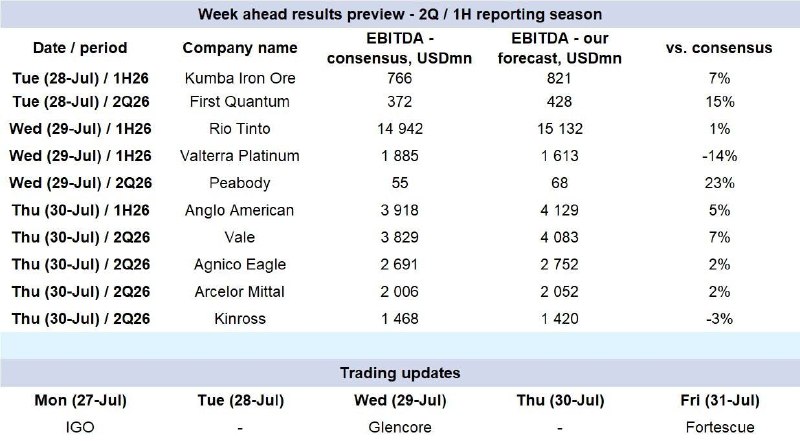
As the reporting season continues, some global miners are scheduled to release their 1H/2Q26 financials this week. Overall, we are broadly in line with the consensus on most of the majors’ EBITDA, but slightly more upbeat on the performance of Glencore and Torex

#reporting_season
Post #2622 139
Morning Bites

🏆Global physical gold demand increased 7% YoY to 987t in 2Q26 (also being 46% higher YoY in value terms, as gold prices were up 37% YoY in 2Q26), vs. the revised 9% YoY decline in 1Q26, per World Gold Council data. Specifically, gold jewellery demand dropped 12% YoY in 2Q26, but central bank purchases surged 62% YoY. Among other key demand segments, a moderate decline was recorded in Bars&Coins (-3% YoY)

Despite overall solid physical purchases, total gold demand was unchanged YoY in 2Q26 in volume terms, as global ETF holdings contracted (by 45t net in 2Q26), affected by expectations of tighter monetary policy in the US. Meanwhile, world mined gold output grew 2% YoY in 2Q26

#gold
Post #2621 135
Morning Bites
 
💍LVMH's organic sales of watches and jewellery increased 11% YoY in 2Q26, compared with the 7% YoY gain in 1Q26, the company revealed in a press-release. LVMH reported solid first‑half results, while stressing that its operating environment remains unsettled and further strained by the conflict in the Middle East

We maintain our cautious view on the prospects for global diamond market recovery in 2026. Risks to supply discipline remain, as Anglo American's planned sale or spinoff of De Beers undermines market participants' confidence in price-over-volume strategy. Meanwhile, geopolitical concerns keep weighing on consumer sentiment

#diamonds
Post #2620 132
Morning Bites

🔗CISA mills daily crude steel production in mid-July was 2.015mnt, down 0.3% from the previous ten days, and 5.9% lower YoY. Per CISA data, local production has declined 5.4% YTD (through 20 July). Meanwhile, local steel inventories expanded 8.1% over the period and were also 15.8% higher YoY

Given the ongoing weakness in the global steel market, we believe that Beijing will continue to gradually tighten supply. Although the current five-year plan lacks explicit targets for capacity cuts, it is our view that China might also introduce additional strict supply-control measures, similar to the 2016-17 reform (when >100mnt steelmaking capacity was removed)

For instance, Beijing has recently imposed a more stringent steel capacity swap plan to curb oversupply. Per a Ministry of Industry and Information Technology statement, at least 1.5t of old steel capacity must now be decommissioned to build ⁠every 1.0t of new capacity nationwide

#steel
Post #2619 143
Morning Bites

🥉Global mined copper production declined 3.3% YoY in May, vs. the drop of 4.4% YoY in April, the ICSG reports. Overall, in 5mo26, global copper output decreased 1.9% YoY. The main contributors to the production slowdown were Indonesia and Chile, where mined production declined 38.0% and 8.8% YoY, respectively, affected by major accidents in 2025 and declining ore grades

Meanwhile, global apparent copper consumption increased 2.2% YoY in 5mo26, mainly driven by Chinese demand (+3.0% YoY)

We maintain our bullish view on copper, due to both short- and long-term supply issues, growing global demand for renewables and surging investments in China’s grid infrastructure (~8% of global Cu demand, on our numbers)

#copper
Post #2618 131
Morning Bites

🚘EU + UK passenger car registrations rose 13% YoY in June, accelerating from the 4% YoY gain in May, per ACEA data. The result was broadly in-line with preliminary estimates, although volumes remained 6% lower than the pre-Covid level (June 2019). Specifically, local ICE vehicles (with catalytic converters) sales increased 4% YoY, while BEV registrations jumped 55% YoY last month

We believe that tightening PGM supply (e.g., recent long-term SBSW guidance), the cancellation of EV subsidy programmes in the US (from late-September 2025), as well as potentially higher PGM autocatalyst loadings in China in the coming years (due to planned China 7 emissions standard), could support Pd/Pt market fundamentals in the medium term

In 2025, the EU+UK represented approximately 23% and 25% of global autocatalyst demand for palladium and platinum, respectively

#cars
Post #2617 127
Week ahead data releases in M&M

As the reporting season continues, some global miners are scheduled to release their 1H/2Q26 financials this week. Overall, we are broadly in line with the consensus on most of the majors’ EBITDA (except for Valterra)

#reporting_season
Post #2616 161
Morning Bites

🔗Global crude steel output increased 2% YoY in June to 156mnt, vs. the broadly flat YoY dynamics in May, World Steel Association (WSA) data show. China’s production (~54% of global crude steel supply) remained unchanged YoY at 84mnt, implying that world ex‑China output grew roughly 3.3% YoY. Specifically, in June, solid production gains were recorded in the EU (+5% YoY), India (+5% YoY) and the US (+4% YoY), while Russia’s supply dropped 3% YoY

Given the ongoing weakness in the global steel market, we believe that Beijing might continue to tighten supply on a gradual basis. Specifically, in May, China’s Ministry of Industry and Information Technology released a tougher steel capacity swap plan to curb oversupply: now at least 1.5t of old steel capacity needs to exit to build ⁠every 1.0t of new capacity nationwide

#steel
Post #2615 131
Morning Bites

💍 Sales at Richemont’s Jewellery Maisons jumped 21% YoY in 2Q26, after the 7% YoY gain in 1Q26, the company has reported in a press-release. Richemont highlighted that the sales growth was supported by robust local demand across key markets and improving tourism trends

Despite the overall solid downstream demand, we maintain our cautious view on the medium-term prospects for a recovery in the global diamond market, given the risks to supply discipline posed by Anglo American's planned sale of De Beers (which is currently disrupting the price-over-volume strategy), as well as geopolitical concerns

#diamonds
Post #2614 168
Morning Bites

💎Burgundy’s Ekati diamond mine is set to shut down by mid-August 2026, as the sales process (triggered by insolvency) did not result in any compliant bids, despite 140 “potentially interested parties” being contacted, Rapaport reports, citing the Supreme Court of British Columbia filings

Overall, the upcoming closure of Ekati mine (2.8% of global mined diamond supply in 2025 and ~4.0% historically), which was originally expected to operate at least until 2029, underpins severe operational challenges among junior miners (~⅓ of global rough supply) and still weak market sentiment

We maintain our cautious view on the medium-term prospects for a recovery in the global diamond market, given the risks to supply discipline posed by Anglo American's planned sale of De Beers (which is currently disrupting the price-over-volume strategy), as well as geopolitical concerns

#diamonds
Post #2612 124
Morning Bites

🏭Global primary aluminium output declined 1.5% YoY in June, after the 1.6% YoY decrease in May, per IAI data. Chinese supply (62% of global Al output) grew 1.8% YoY last month. Although local Al output — 45.1mnt annualised in 1H26 — technically exceeded the cap of 45.0mnt/year (amid utilisation of previously unused quotas, etc), we do not expect the additional volumes to surpass 1.0mnt

Meanwhile, the output of Gulf nations (9% of global Al supply in 2025) shrank 34.5% YoY in June, amid the US-Iran conflict. Specifically, ~60% of the region's Al operations have been affected to various extents since late-February (e.g., UAE’s EMAL, Bahrain’s Alba, and Qatar’s Qatalum). Given the nature of the damage, we anticipate sluggish production dynamics in the region until the end of the year

We maintain our view that strong consumption dynamics in Asia (including grid), combined with concerns over global supply, are likely to provide support for the Al price, which we forecast to average USD ~3,400/t in 2026F

#aluminium
Post #2611 140
Morning Bites

🔗CISA mills daily crude steel production in early-July was 2.02mnt, unchanged from the previous ten days, but 3.6% lower YoY. Per CISA data, local production has declined 5.4% YTD (through 10 July). Meanwhile, local steel inventories expanded 3.0% over the period and were also 11.3% higher YoY

Given the ongoing weakness in the global steel market, we believe that Beijing will continue to gradually tighten supply. Although the current five-year plan lacks explicit targets for capacity cuts, it is our view that China might also introduce additional strict supply-control measures, similar to the 2016-17 reform (when >100mnt steelmaking capacity was removed)

For instance, Beijing has recently imposed a more stringent steel capacity swap plan to curb oversupply. Per a Ministry of Industry and Information Technology statement, at least 1.5t of old steel capacity must now be decommissioned to build ⁠every 1.0t of new capacity nationwide

#steel
  • ❤ 1
Post #2610 126
Week ahead data releases in M&M
  
As the reporting season continues, several major M&M names are due to publish their 2Q26/1H26 results this week. Overall, our EBITDA forecasts are moderately more bullish than the consensus, except for Teck

Also of importance this week are Thursday's scheduled publication of both the official EU car sales data and global steel production numbers for June

#reporting_season
Older posts →
Threads Profile ViewerView any public Threads profile without an account.Open ThreadLook →Writing with AI? Make it sound human.Metric37 rewrites AI drafts so they read naturally. Free AI detector, 1,500 words free.Try Metric37 →