
The model doesn't "predict the market."
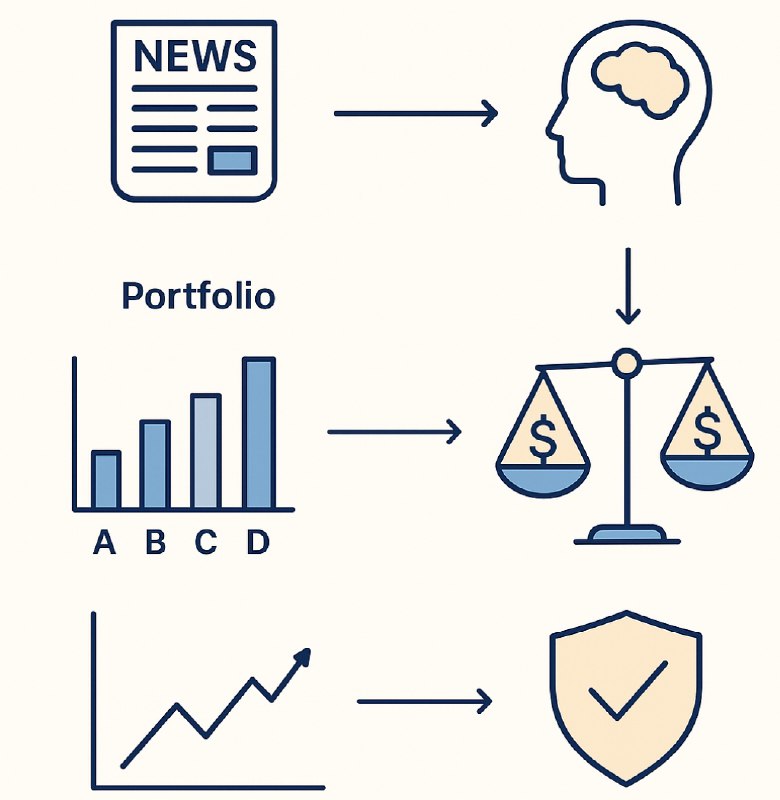
It simply *reads the news* and refines the classic factor by adding a filter of the real information background.
🟢 How does this idea work?
Classic momentum buys recent "winners" but doesn't consider what the news says.
This work added a semantic filtering layer: the model reads fresh headlines and gives each company a score between 0 and 1.
Then the portfolio is reshuffled: a higher score means more weight.
Sharpe ratio increases from 0.79 to 1.06, lower volatility and drawdowns, higher return per unit of risk
Momentum + current headlines → smarter, more stable, safer.
Also... why does GPT-5 trade so poorly then? Trading≠momentum
🤖 Data Science, ML & Big Data with @DataXplore